
Published: 15 December 2025. The English Chronicle Desk. The English Chronicle Online.
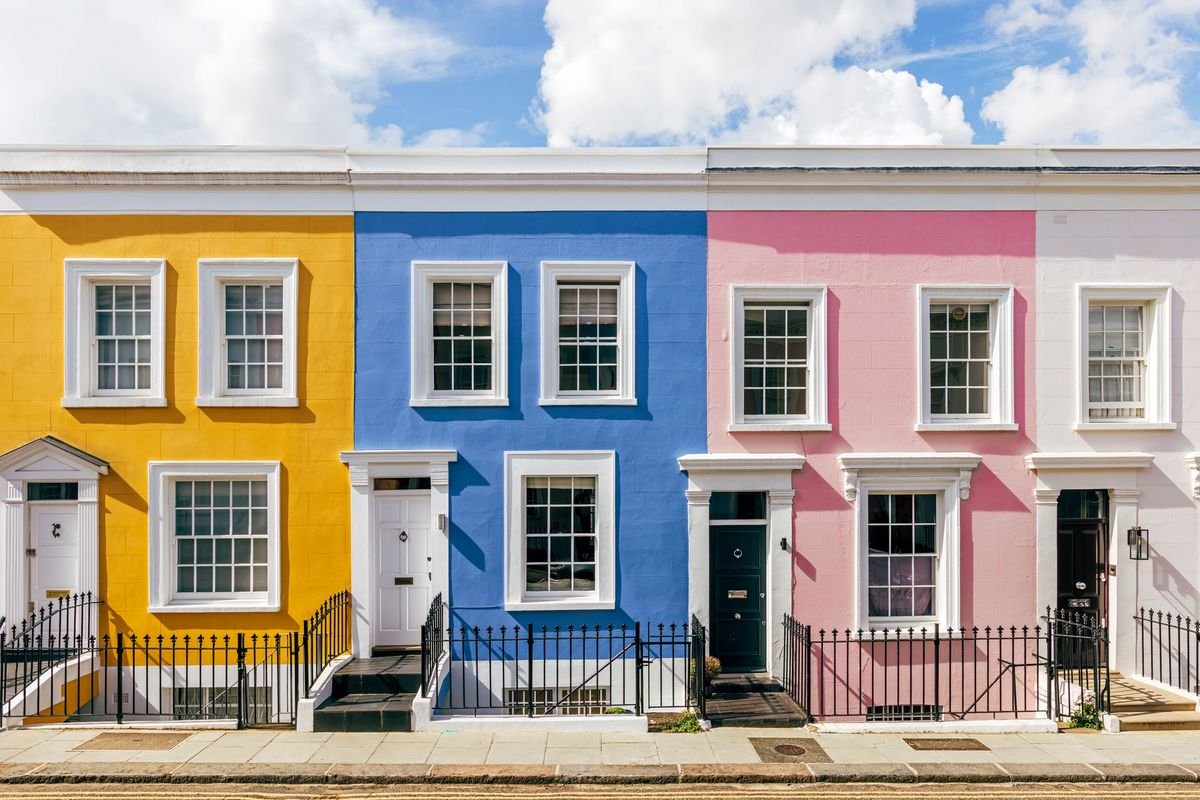
First-time buyers in the UK are now taking out larger mortgages than ever before, as rising wages and looser affordability rules allow access to homes previously out of reach. Analysis by property agent Savills reveals that the average first-time buyer borrowed £210,800 in the year to September, marking a record high in borrowing. This surge demonstrates how the market is shifting to accommodate younger buyers with growing financial confidence.
First-time buyers accounted for 20% of all housing market spending in the 12-month period, the highest proportion since at least 2007. In London, this effect is even more pronounced. Research by estate agent Hamptons shows that more than half of all property purchases in the capital this year were made by first-time buyers.
Savills reported that lenders provided a record £82.8 billion in mortgage loans to 390,000 first-time buyers during this period, representing a 30% increase compared to the previous year. Many of these borrowers opted for houses rather than flats, skipping the traditional first step of the property ladder. The average age of a first-time buyer now stands at 34, with 31% already having children by the time they purchase their first home, according to the Mortgage Advice Bureau.
A major incentive has been the stamp duty holiday, which allowed first-time buyers to pay no tax on the first £425,000 of a property’s value. Although this threshold fell back to £300,000 in April, many buyers still benefited from falling property prices in certain areas, creating a favourable “buyer’s market.”
Lucian Cook, head of residential research at Savills, noted that a key driver of the record borrowing was the “slightly more relaxed approach” of lenders. He explained, “Home ownership is more accessible now than at any point in the last three years, thanks to lower borrowing costs, lower real house prices, and more accessible mortgage debt.”
Mortgage providers typically limit borrowing to 4.5 times a borrower’s income while performing stress tests to assess affordability if interest rates rise. In March, the Financial Conduct Authority (FCA) warned that some lenders’ stress tests might “unduly restrict access to otherwise affordable mortgages.” Following this guidance, most lenders reduced the interest rate used for stress testing, allowing first-time buyers to borrow an additional £20,000-£40,000.
This relaxation coincides with a decline in mortgage rates. Moneyfacts reports that the average two-year fixed mortgage is now 4.91%, and a five-year fix is 4.86%, levels last seen before the economic instability triggered by Liz Truss’s mini-budget in September 2022.
House prices are also reflecting this dynamic. Rightmove reports that buyers could secure a property for about £2,000 less than a year ago and £6,700 less than the previous month. Across the UK, average asking prices in December 2025 stand at £358,138, 0.6% lower than a year ago and 1.8% lower than in November.

Regional variations show the strongest annual price growth in the north-west of England at 2.6%, while London remains flat. The south-west and south-east saw declines of 2.7%. December typically sees price falls, but this year’s drop has been larger than usual. However, Rightmove predicts a larger-than-usual “Boxing Day bounce,” as buyers resume house hunting after holiday delays caused by budget uncertainty.
This combination of relaxed mortgage rules, lower interest rates, and slightly reduced property prices has created a window of opportunity for first-time buyers, allowing them to secure larger properties than previously possible. The evolving housing market suggests that younger buyers may continue to play a dominant role in shaping property trends into 2026.
Related News:
 Peterborough Mosques Tighten Security After Attack
 Reeves Faces Setback as Labour May Miss Homes Target
 Hospice Cuts Raise Alarm Across England Amid Funding Crisis
 Virgin Trains Moves Closer to Challenging Eurostar Monopoly
 Kate Winslet to Narrate Film Highlighting King’s Environmental Mission
 Green Party Surges Past Labour in Latest UK Poll
 Army Officers Orders to Cut Ties with Men-Only Clubs
 Trump’s UK Ambassador Urges North Sea Drilling to Strengthen US Ties
 Children to Learn Local History in Major Curriculum Overhaul
 Ryanair Chief UK Economy ‘Doomed’ Under Labour
 French Taxi Driver Cleared in David Lammy Theft Case After Fare Dispute
 UK Bans Fake Numbers: Scammers Lose Their Trick
 Prince William Plants Trees with Brazil’s Nature Heroes
 M&S Profits More Than Halve After Cyber-Attack
 Kent village told to remove flags before Christmas lights go up
 Vibe coding’ named Collins dictionary’s word of the year
 Labour immigration crackdown could cost UK £4.4bn
 Patients to Test Health at Home to Ease NHS Winter Pressure
BBC to Apologise Over Edited Trump Speech Amid Backlash
 King Charles to Lead Nation in Remembrance Sunday Service
 Britain deploys RAF specialists to assist Belgium with drone threats
 Palace May Restore Hyphen to Andrew Mountbatten-Windsor’s Name
 Millionaires group urge Reeves to introduce wealth tax to ‘lift kids out of poverty’
 Starmer Faces Growing Dissent as Labour MPs Weigh Leadership Challenge
 From Lego to Pokémon: How Adults Are Driving UK Toy Market Growth
 Shouting Works Best to Deter Gulls, UK Study Finds
 Reeves rejects £1bn plea for NHS redundancy payouts
 Stop using ChatGPT to write speeches, AI minister tells MPs
 Northern Lights may illuminate UK skies this week
 UK and Ireland Announce Venues for Euro 2028 Tournament
 PM Condemns Leaks, Vows Loyalty to Ministers and Stability
 Son Reveals UK Couple in Iran Resort to Hunger Strike for Help
 TalkTV Fires Mike Graham Over Racist Facebook Post
 Phillipson Accused of Appeasing Unions by Diluting EBacc
 Major Rent Reform Ends No-Fault Evictions in England
 Senator John Fetterman Hospitalized After Fall from Heart Flare-Up, Keeps Sense of Humor
 Saka Solidifies Role as Tuchel’s Key England Lieutenant
 Former Lion Heskey Warns of Shortage of England Strikers
 New AI tool could cut wasted efforts in organ transplants
 Greene Pushes Epstein Files Amid Trump Fallout
 Trump Deploys DHS to Charlotte in Major Arrest Operation
 December Run-Off in Chile as Election Produces No Winner
 Criminal Gangs Pose as Truckers to Hijack UK Supply Chains
 Zelenskyy Signs Fighter Jet Deal Amid Russian Drone Attacks
 Orban Says Ukraine Has ‘No Chance’ as EU Support Continues
 Stroke Patient Mistaken for Drunk, Care Delayed
 Canada Passes Carney’s First Budget in Tight Parliamentary Vote
 Sundar Pichai Cautions on AI Hype and Market Risks
 Google Chief Urges Caution: Don’t Trust AI Blindly
 What Now for the Queen’s Childhood Playhouse After Andrew’s Eviction?
 Van Dwellers Face Eviction After Park Misuse Sparks Outcry
 Shadow Fleet at Sea: Europe’s Battle Against Illicit Oil Shipping
 ‘Traumatic Wait’: Northern Ireland Women Face Breast Cancer Delays
 Tiny Curacao Makes History as Smallest Nation to Reach World Cup
 Deadly Russian Strikes Hit Western Ukraine, 20 Killed in Ternopil
 Snow and Ice Cause Travel Chaos in North Yorkshire
 Serial Rapist and Former Cop Found Guilty Again
 Man Denies Stealing Bronze Age Gold from Museum
 Ukraine Peace Plan: Zelensky Ready for Dialogue
 Director Michael Caton-Jones Reflects on Career and Beginnings
 Scottish Families Take Legal Action Over School CO Leak
 Royal Navy Shadows Russian Warships Entering the Channel
 Inside the Helpline Protecting Missing Children in the UK
 Most Tories Expect to Support a Farage-Led Government
 Boots Showstopper Beauty Bundle Outshines Many Advent Calendars This Holiday Season
 Labour’s ‘blinkered’ drive to build risks pushing wildlife to point of no return, nature experts warn
 PlayStation PS5 Deals Hit Lowest Prices Ahead of Black Friday
 Karen Carney Stuns on Blackpool Week, Deserves Strictly Final
 Runaway Driver Caught by DNA Evidence
 US Suspends Afghan Immigration After White House Shooting
 Georgians Defy Government Crackdown After Year of Protests
 US National Guard Member Killed in DC Shooting
 Five-Year-Old Dies After Rare Tonsil Surgery Complication
 ICC to Rule on Duterte’s Provisional Release
 Tokyo court rules Japan’s same-sex marriage ban constitutional
 Starmer Says Labour’s Economic Plan Needs Years to Deliver
 Rusty Bond-Era Aston Martin Restored to £1m Glory
 More Patients Now Contacting GPs Online, Data Shows
 ‘Extinct’ Antelope Returns to Sahara, Bringing Hope
 IndiGo Cancels Hundreds of Flights Amid Pilot Shortages