
Published: 17 October 2026. The English Chronicle Desk. The English Chronicle Online
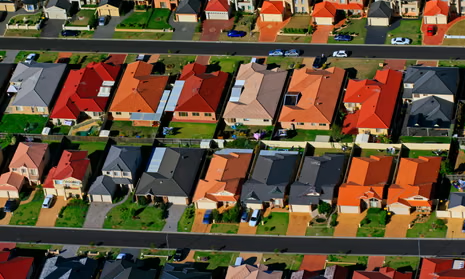
Australia’s housing market is entering an unusual phase in which buying a home is becoming financially competitive with renting in an increasing number of suburbs, offering some tenants a potential pathway to homeownership after years of rising property costs. New analysis of housing data shows that mortgage repayments are now lower than typical rents in certain Australian locations, while in many other suburbs the difference between the two options has narrowed considerably.
The shift comes as rental prices continue to climb and residential property values have begun to level off following a period of decline in several markets. Although purchasing a home remains expensive across much of Australia, the changing relationship between mortgage repayments and rents is encouraging some tenants to reconsider whether continuing to rent is the most financially practical long-term decision.
An analysis by Guardian Australia using data from property research firm Cotality found that median rents in parts of inner Melbourne, suburban Canberra and Darwin are approaching the weekly repayments required to purchase a typical property. In some locations, mortgage repayments have already fallen below the equivalent rental cost, creating a rare opportunity for households that can meet the deposit and lending requirements.
The findings suggest that Australia’s housing affordability debate is becoming more complicated. For years, rapidly rising property prices and substantial mortgage commitments made renting the more accessible option for many households, particularly younger people and first-time buyers. However, rising rents and weaker property prices are beginning to change that calculation in selected areas.
Nationally, Australia’s median weekly rent increased by 5.5 per cent over the 12 months to September 2026, reaching $713, according to Cotality data. Over the same period, the median value of residential properties, including houses and units, remained broadly unchanged after six consecutive months of steady declines.
The figures illustrate two contrasting trends. Rental costs continue to rise as tenants compete for available accommodation, while the slowdown in property values is reducing the purchase price of some homes. Together, these developments are narrowing the financial gap between renting and buying, although the benefits vary significantly depending on the location, property type and buyer’s financial circumstances.
Melbourne provides one of the clearest examples of this changing relationship. The typical weekly rent for an apartment in the city reached $628 after increasing by 4.8 per cent over the previous year. However, the estimated weekly mortgage repayment on a typical flat was approximately $839, leaving buyers paying around $211 more each week than renters.
The calculation was based on a median apartment value of $624,740 in September, nearly $25,000 lower than a year earlier. Despite the decline in property values, repayments remained substantially higher than rents across the wider Melbourne apartment market.
Nevertheless, the overall figures conceal important differences between individual suburbs. In Carlton, Melbourne’s central business district, Notting Hill, Travancore and Southbank, estimated mortgage repayments on typical properties were lower than the corresponding rental costs. These locations demonstrate how local housing conditions can create opportunities even when buying remains more expensive across the broader metropolitan market.
The calculations assume a newly arranged 30-year mortgage covering 95 per cent of the property’s value, with an annual interest rate of 6.2 per cent. This means the buyer contributes a deposit equivalent to 5 per cent of the purchase price and borrows the remainder.
The figures provide a useful comparison between mortgage repayments and rent, but they do not represent the full cost of owning a property. Homeowners must also consider expenses such as council rates, insurance, maintenance, repairs and, for apartment owners, strata fees. Transaction costs and other charges associated with purchasing a property can further increase the financial burden.
The assumed deposit is also important. Buyers seeking to purchase with a deposit of just 5 per cent would typically need to qualify for an eligible low-deposit arrangement, such as a government-supported scheme designed to assist first-home buyers. Not every prospective buyer will meet the relevant eligibility requirements, and lenders must still assess income, existing debts, living expenses and the ability to service the proposed mortgage.
For households able to provide a larger deposit, the financial comparison can look more favourable. Borrowing a smaller amount generally reduces monthly repayments and the total interest paid over the life of a loan. However, saving a substantial deposit can take years, particularly for renters whose household budgets are already under pressure from increasing accommodation costs.
Mortgage broker Clint Waters, director of Axton Finance in Melbourne, said interest in purchasing homes had declined, but enquiries from renters considering buying had increased. He described the difference between renting and buying as narrowing, with prospective buyers increasingly examining whether the financial figures now work in their favour.
Some tenants are also considering buying the properties they currently occupy. This approach can be attractive because it may allow them to become homeowners without moving to another suburb, changing schools or disrupting established family and work arrangements.
Waters said landlords facing mounting costs were increasingly considering selling their properties, creating situations in which existing tenants might explore purchasing directly from their landlords. Such arrangements can potentially reduce the disruption associated with moving, although any sale still depends on agreement between the parties, financing and the usual legal requirements.
Sydney is also showing signs of a narrowing gap between rental costs and mortgage repayments. In the inner-city suburb of Ultimo and the western suburbs of Warwick Farm, Rosehill, Liverpool and Granville, estimated weekly repayments were approximately $100 higher than typical rents.
Although buying remained more expensive in these locations under the analysis, the smaller difference could make ownership more attractive to households with sufficient savings and stable incomes. For prospective buyers, a difference of around $100 per week may be easier to evaluate against the long-term benefits of ownership than the much larger gap found in some of Australia’s more expensive housing markets.
Canberra has also emerged as a market where the cost of buying is approaching the cost of renting. In Belconnen and Phillip, estimated mortgage repayments were less than $75 per week above typical rents. When the comparison was limited to apartments, Braddon, Lyons, Gungahlin and Harrison also appeared among the suburbs where the financial difference was relatively small.
One explanation for these patterns is the growth in apartment construction. Areas that have experienced substantial new housing development may have more properties available for prospective owner-occupiers, putting downward pressure on purchase prices. At the same time, rental markets can remain relatively tight, allowing landlords to charge higher rents.
Gerard Burg, a researcher at Cotality, said suburbs with significant apartment development often showed a smaller gap between buying and renting. In some locations, newly built apartments are being sold directly to owner-occupiers rather than being purchased primarily for investment and subsequently offered to tenants.
The additional supply can increase competition among sellers, while limited rental availability pushes rents higher. This combination can create circumstances in which purchasing an apartment becomes comparatively affordable, even though the wider housing market remains difficult for many households.
Burg cautioned, however, that properties where mortgage repayments are lower than rent remain exceptions rather than the national norm. Houses, in particular, generally continue to cost more to purchase than to rent when weekly mortgage repayments are compared using similar assumptions.
He explained that if buying a property were consistently cheaper than renting across the market, more households would have an incentive to purchase and fewer would remain tenants. The fact that renting continues to be cheaper in most areas demonstrates that the housing affordability problem has not disappeared.
Darwin presents a particularly striking example of how local economic conditions can influence the balance. Cotality’s analysis found that purchasing was cheaper than renting in approximately a quarter of the city’s suburbs. Rents in Darwin had increased by 11.6 per cent over the previous year, placing additional pressure on tenants and making ownership comparatively attractive in some neighbourhoods.
However, the city’s housing market has characteristics that distinguish it from larger metropolitan areas. Burg noted that many locations where buying appeared cheaper were associated with mining and resource projects. Workers who travel to such areas for temporary assignments may prefer to rent accommodation rather than purchase homes, creating a distinctive rental market that does not necessarily reflect the circumstances of permanent residents.
This distinction is important for anyone considering buying a property solely because the estimated mortgage repayment is lower than the rent. Local employment conditions, population movements, future housing supply and the potential resale value of a property can all affect whether a purchase remains financially sensible over time.
Interest rates will also play a decisive role in determining how the relationship between buying and renting develops. Mortgage repayments depend not only on property prices but also on the interest rate attached to the loan. When borrowing costs rise, repayments can increase even if house prices fall. Conversely, lower interest rates can improve affordability for buyers, provided lenders are willing to extend credit and household incomes remain sufficient.
In the past year, repayments on newly arranged mortgages increased in many suburbs because interest rates rose by approximately one percentage point, offsetting the benefits of lower property values. In locations where property values declined by more than 10 per cent, however, the fall in purchase prices was more likely to reduce the estimated repayment burden.
Burg said the gap between buying and renting could narrow further if the Reserve Bank of Australia kept interest rates stable while property values continued to fall, as financial markets had anticipated. If rents continued rising or remained broadly unchanged, the relative cost of homeownership could become more attractive in additional suburbs.
Nevertheless, future interest-rate decisions and property-price movements remain uncertain. Buyers who make decisions based on expectations of falling prices or lower borrowing costs could face financial difficulties if market conditions develop differently from forecasts.
For renters, the latest figures provide a reason to reassess their options rather than assume that homeownership is automatically out of reach. Comparing the cost of a mortgage with rent can help households understand whether buying is financially feasible, but the assessment should also account for deposits, borrowing capacity, ownership expenses and the need to maintain an emergency savings buffer.

The emerging trend does not mean Australia has solved its housing affordability crisis. High purchase prices, deposit requirements and lending restrictions continue to prevent many renters from entering the property market. In addition, a mortgage that appears comparable to rent on a weekly basis may involve considerably greater financial risk because borrowers remain responsible for their debts even if their circumstances change.
Even so, the narrowing gap represents a meaningful shift in parts of the housing market. After years in which renters often faced escalating costs while property ownership appeared increasingly distant, selected Australian suburbs are offering a more competitive comparison between the two options.
Whether this window remains open will depend on the direction of rents, property prices, interest rates and the availability of new homes. For now, the figures suggest that some Australian tenants may be closer to homeownership than they were a year ago, although the opportunity remains highly dependent on where they live and whether they can meet the financial requirements of buying a property.
Related News:
 France Faces Debt Crisis as Protests and Markets Clash
 Weight-Loss Drugs Transform Fashion Shopping Habits
 Dutch Bank Moves 86 Tonnes of Gold to London
 UK House Prices Fall as Mortgage Rates Rise
 Oil nears $100 as Saudi attacks shake markets
 Thames Water Revises Oxfordshire Mega-Reservoir Plan
 Japan Raises Rates to 31-Year High
 Thinktank Calls for Abolition of UK State Pension
 Saudi intercepts Houthi missiles as oil fears grow
 Ukraine Faces $45m Hourly Cost From Missile Alerts
 Poundland Rescue Bid Could Protect 11,000 Jobs
 French Debt Fears Put Euro Markets Under Pressure
 UK Diesel Reaches £2 as Inflation Surges Across Europe
 Minister Rejects Fears of UK Diesel Shortage
 EU-China Talks Target Surge in Hybrid Car Imports
 Ministers Push ATO to Reconsider Credit Card Ban
 Oil Shock Sends Markets Lower as Middle East Risks Grow
 Australia Delays Tax Credit Card Payment Ban After Backlash
 Firmus Abandons Major ASX Listing Amid Investor Doubts
 Trader Wins Unfair Dismissal Case After Overseas Work
 Hanson Attacks Taylor as Australian Conservatives Clash
 UK Savers Face Uncertainty as Rates Rise Above 5%
 Hall and Woodford Win Nobel Economics Prize
 IMF Warns Global Economy Is Nearing Its Limits
 Global markets face turmoil as Hormuz crisis deepens
 UniCredit’s Bold Move to Reshape European Banking
 Ukraine Urges UK to Seize Russian Oil Tankers
 $13bn World Cup Set to Break All Revenue Records
 US Awaits Iran Reply on New Ceasefire Proposal
 EasyJet Takeover Sparks Fears Over Passengers’ Future
 Weight-Loss Drugs Offer Food Savings Mainly to High Earners
 Canada to Match Trump’s 50% Tariffs Dollar for Dollar
 Pubs and Hotels Face Business Rates Reform Review
 Firms on both sides fear damage from US-Canada trade war
 Europe Faces Winter Gas Supply Anxiety
 UK Households Could Save £173 on Fixed Energy Deals
 Trump Hardens Canada Trade Stance as Talks Stall
 Green Leader Targets Starmer’s Former Seat
 UK Subsidence Claims Surge After Record-Breaking Summer
 Billionaire Chris Rokos poised to leave UK
 JPMorgan Boss Warns Against UK Bank Tax Rise
 Saudi Arabia Shuts Oil Pipeline After Drone Attack
 Oil Prices Surge as Saudi Pipeline Closure Deepens Crisis
 UK Retailers Accused of Breaking Refund Laws
 UK Pay Growth Slows to 3.9% as Rate Decision Nears
 Bank Urged to Slow Bond Sales as UK Costs Rise
 UK Inflation Hits 3.1% as Household Pressure Grows
 UK Retail Sales Rebound as Consumers Spend More
 UK Rent Gap Puts Low-Income Families Under Pressure
 Trump Eyes Major Belarus Fertiliser Deal Amid Canada Trade Dispute
 MPs Defend UK Economic Watchdog Against Critics
 Iran Rejects Claims of Shift in US Talks
 Trump gives Xi red-carpet welcome as trade truce extends
 Chinese Hybrid Car Surge Raises EU Auto Industry Concerns
 Tony Blair Calls for Britain to Rejoin EU Within a Decade
 Should Savers Lock Into 5.25% Fixed Rates?
 Burnham Opens Door to Possible UK Return to EU
 Healey urged to act as UK energy bills rise 4%
 UK house price growth slows as mortgage rates rise
 UK borrowing costs surge as global bond sell-off deepens
 Boots Sale Nears as Weston Family Eyes $9bn Deal
 UK Assures Public Over Diesel Supply
 Informa Agrees £2.24bn Deal to Buy Clarion
 IMF Warns Governments Over Rising Debt Burdens
 South Korea Probes Fuel Shipments to Russia
 Tesco Raises Profit Forecast as Consumer Confidence Holds
 UK Pharmacy Body Drops Teva After Ethical Concerns
 Turkey Rules Out Troops in Saudi Arabia’s Houthi Conflict
 Three Convicted in Mexico Surfing Trip Murders
 Australian Advocates Seek Subsidised Drugs for PMOS
 Australia Rejects Russian Fuel as Trump Strikes Deal
 IFS Warns UK Budget Faces £35bn Spending Gap
 Brazil Court Scandal Threatens Lula as Bolsonaros Rise
 Millions Face Tougher Medicaid Rules From January
IMF Raises UK Growth Forecast Ahead of Healey’s Budget
 Healey Plans £1bn Online Marketplace Tax Crackdown
 UK Water Firms Face £107m Bill Reduction Penalties
 Trump Rallies GOP as Senate Democrats Boost Key Races
 UK Could Rejoin EU Through a Switzerland Plus Deal
 Trump Halts New Russia Sanctions Amid Ukraine Rift