
Published: 07 October 2026. The English Chronicle Desk. The English Chronicle Online
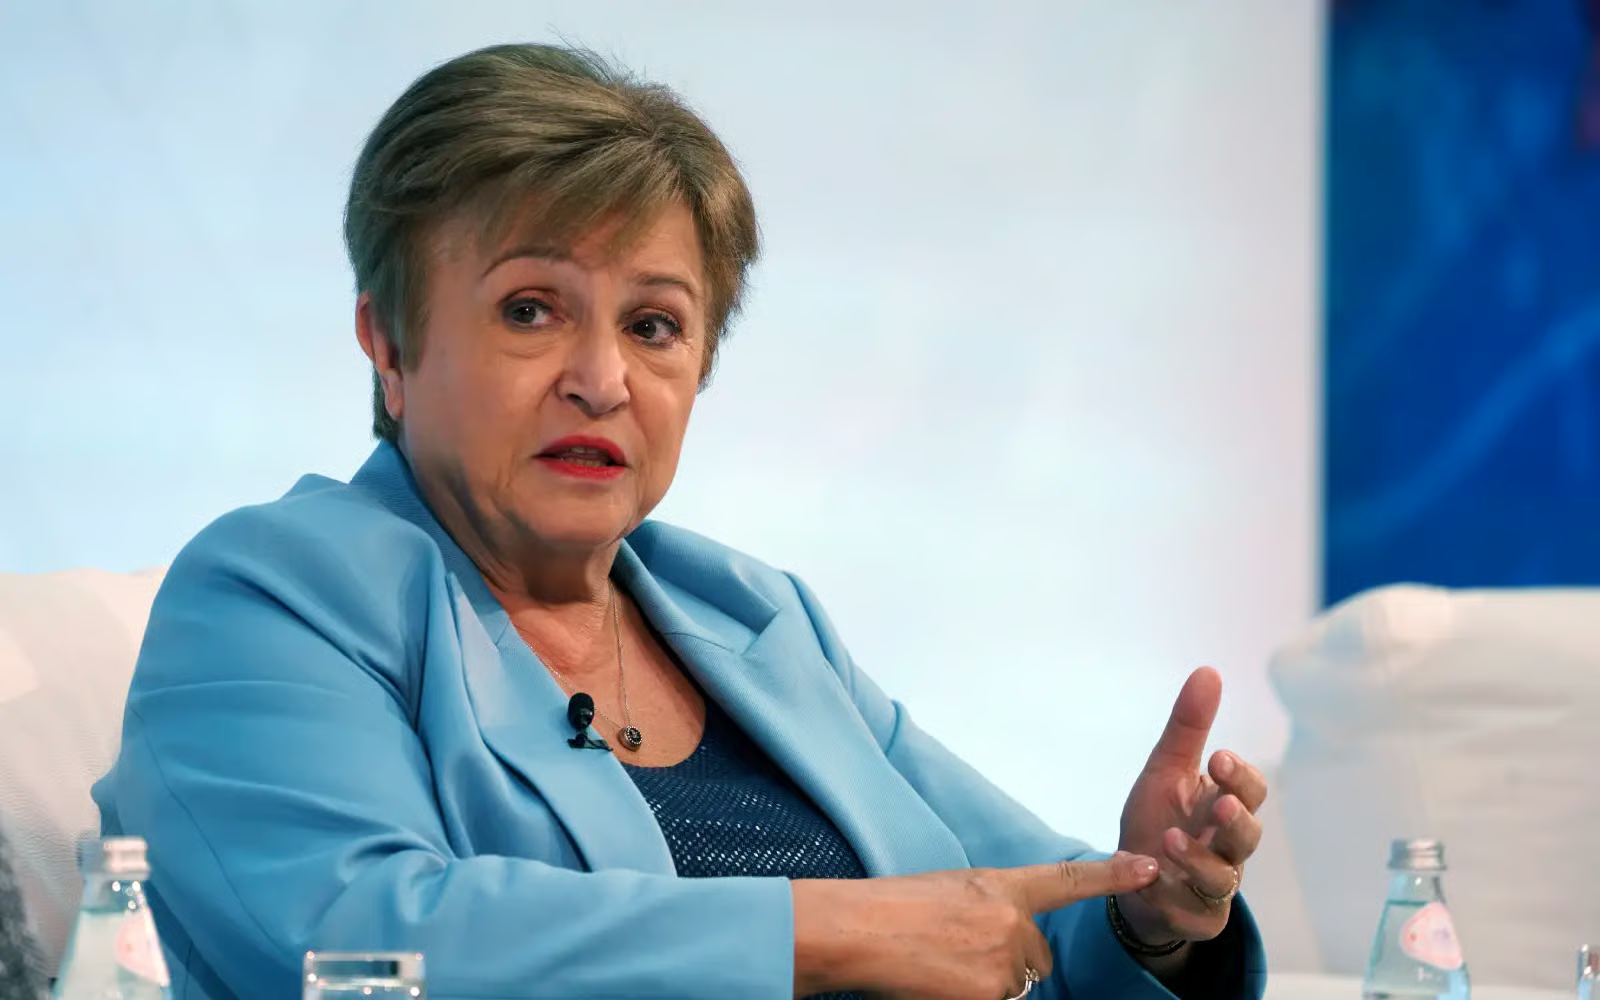
The managing director of the International Monetary Fund, Kristalina Georgieva, has urged governments in major economies to tighten their fiscal policies as rising borrowing costs and historically high levels of public debt place growing pressure on national budgets.
Speaking in Singapore ahead of the annual meetings of the IMF and World Bank in Bangkok next week, Georgieva warned that governments could no longer depend on rapid economic growth to solve their debt problems. With global debt levels continuing to climb and bond yields increasing, she said policymakers were approaching a period in which difficult political decisions would become unavoidable.
Global debt relative to economic output is now at its highest level since the Second World War, according to Georgieva, and the ratio is expected to approach 100% of global gross domestic product in the coming years. Such a level would leave governments with significantly less room to respond to economic shocks, particularly as defence, social programmes, infrastructure and other public spending demands compete for limited resources.

Georgieva said policymakers had already been given the tools needed to address the situation but had been too slow to use them. Her warning comes as financial markets have become increasingly concerned about inflation, government borrowing and the sustainability of public finances across several major economies.
“My message to the world’s economic policymakers will be this: we cannot keep delaying necessary policy action,” Georgieva said. She argued that governments should now use the available policy instruments with greater determination rather than postponing difficult decisions.
The IMF chief said highly indebted advanced economies needed credible medium-term plans to bring their finances under control. In some cases, she indicated, governments would need to introduce measures immediately rather than relying entirely on gradual adjustments over several years.
The pressure has become more visible in government bond markets. Bond yields, which broadly represent the interest rates governments must pay when borrowing, have risen sharply in recent weeks. Higher yields mean that refinancing existing debt and issuing new debt becomes more expensive, increasing the amount governments must allocate to interest payments.
The increase in borrowing costs is particularly significant because many governments already face substantial debt obligations accumulated during years of economic disruption, including the Covid-19 pandemic and subsequent energy and inflation shocks. As interest payments consume a larger share of government revenues, policymakers have less flexibility to fund other priorities without raising taxes, cutting expenditure or borrowing more.
Georgieva pointed to defence spending as one of the areas competing for increasingly scarce public funds. Governments in Europe and elsewhere are under pressure to increase military expenditure amid heightened geopolitical tensions, while households and businesses continue to face the consequences of elevated living costs.
The situation is further complicated by renewed concerns about inflation. Higher energy costs associated with conflict in the Middle East have contributed to uncertainty over the future path of prices and economic growth. Financial markets have responded by reassessing expectations for interest rates and government borrowing.
Against that background, Georgieva suggested that central banks should remain prepared to respond firmly if inflation begins to accelerate again. She said a cautious approach to monetary policy could be appropriate in many countries, effectively warning policymakers not to assume that inflationary pressures have permanently disappeared.
The European Central Bank, US Federal Reserve and Bank of Japan have already moved to tighten monetary policy in response to renewed inflationary pressures. Georgieva described those decisions as appropriate, while highlighting the possibility that other central banks may also need to maintain a more cautious stance.
In the United Kingdom, the Bank of England has so far kept its interest rate at 3.75%. The decision comes as the British economy faces the difficult combination of weak growth, high public debt and continued pressure on household and government finances.
Higher interest rates can help contain inflation by reducing demand, but they can also increase the cost of mortgages, business borrowing and government debt. Policymakers therefore face a delicate balancing act between protecting price stability and avoiding additional damage to economic activity.
For governments, the combination of higher bond yields and large debt burdens presents a particularly difficult challenge. When interest costs rise, money that could otherwise be used for public services, investment or tax relief may instead be diverted towards servicing debt.
Georgieva’s warning therefore reflects a broader concern that fiscal and monetary policymakers have entered a more constrained economic environment. During periods of strong growth and low borrowing costs, governments can often manage large debt burdens more easily. But when growth slows and interest rates remain elevated, the same debt can become considerably more difficult to sustain.
The IMF chief also highlighted another major transformation that could influence the global economy: artificial intelligence. The rapid development and adoption of AI has helped support optimism around productivity and economic growth, particularly in the United States, where technology companies have played a major role in the performance of financial markets.
IMF research suggests that effective adoption of artificial intelligence could add around half a percentage point to global economic growth. Georgieva nevertheless stressed that the potential economic gains must be weighed against serious risks.
One of the biggest concerns is the impact of AI on employment. As companies automate increasingly sophisticated tasks, some workers could face displacement, while demand for certain skills could change rapidly. The resulting disruption could deepen inequality if workers and governments are unable to adapt quickly enough.
Georgieva also warned about cybersecurity and financial stability risks associated with increasingly powerful AI systems. More advanced technology could potentially accelerate cyberattacks, amplify financial-market instability and create new vulnerabilities within critical economic systems.
She further raised concerns about frontier AI models becoming difficult for humans to control. The warning reflects growing international debate over how governments should regulate advanced artificial intelligence while still allowing societies to benefit from technological innovation.
The issue has also attracted attention from financial authorities. Bank of England governor Andrew Bailey has previously warned that highly advanced AI systems could pose significant risks to financial stability and argued that regulators should have the ability to intervene where necessary.
For governments already struggling with debt, AI presents both an opportunity and a challenge. Greater productivity could support economic growth and help improve public finances over time, but large-scale labour market disruption could increase pressure on welfare systems and create new demands for public investment in education and retraining.
The UK provides a clear example of the difficult fiscal choices facing advanced economies. Chancellor John Healey has said the government intends to maintain a fiscal framework under which day-to-day spending is covered by tax revenues, while borrowing is primarily used for investment. The broader objective is to reduce the debt-to-GDP ratio over time.
That approach reflects the type of medium-term fiscal discipline Georgieva is encouraging, although maintaining such discipline can become politically difficult when governments face simultaneous demands for higher public spending, stronger defence capabilities and support for households.
The IMF’s warning also comes at a time when investors are paying closer attention to the ability of governments to control debt. Persistent deficits and rising borrowing costs can increase market concerns, potentially pushing yields higher and creating a cycle in which debt becomes progressively more expensive to service.
The challenge for policymakers will therefore be to restore confidence without imposing measures so severe that they undermine economic growth. Excessively rapid spending cuts or tax increases could weaken demand, while insufficient fiscal action could leave governments exposed to higher borrowing costs and future financial shocks.
Georgieva’s message ultimately reflects a changing global economic landscape. The era of exceptionally cheap borrowing and seemingly unlimited fiscal flexibility has become more difficult to sustain. Governments are now being asked to make decisions that could involve unpopular tax measures, spending restraint and long-term reforms.
At the same time, they must prepare for new economic forces, from geopolitical instability and energy-price shocks to artificial intelligence and changing labour markets. The IMF’s central concern is that postponing these decisions could make the eventual adjustment more painful.
As finance ministers, central bankers and economic policymakers prepare to gather in Bangkok, the pressure will be on governments to demonstrate that they have credible plans for managing debt while protecting economic stability. The coming years are likely to test whether major economies can balance fiscal discipline with investment, social protection and the demands of a rapidly changing global economy.
For Georgieva, the message is clear: governments cannot simply wait for growth to solve their debt problems. With borrowing costs elevated and economic risks multiplying, difficult choices may now be unavoidable.
Related News:
 Thinktank Calls for Abolition of UK State Pension
 MPs Defend UK Economic Watchdog Against Critics
 Saudi intercepts Houthi missiles as oil fears grow
 Why Americans Feel Ripped Off by Rising Prices
 Informa Agrees £2.24bn Deal to Buy Clarion
 EU-China Talks Target Surge in Hybrid Car Imports
 BBC News Faces Deep Cuts in 2,000 Job Plan
 Reeves Fights to Keep Treasury Role Amid Labour Turmoil
 Burnham Faces Mounting Budget Challenges
 Dutch Bank Moves 86 Tonnes of Gold to London
 Trump Hardens Canada Trade Stance as Talks Stall
 UK House Prices Fall as Mortgage Rates Rise
 Oil nears $100 as Saudi attacks shake markets
 Thames Water Revises Oxfordshire Mega-Reservoir Plan
 UK Pay Growth Slows to 3.9% as Rate Decision Nears
 Bank Urged to Slow Bond Sales as UK Costs Rise
 UK Inflation Hits 3.1% as Household Pressure Grows
 Japan Raises Rates to 31-Year High
 UK Retail Sales Rebound as Consumers Spend More
 Trump Eyes Major Belarus Fertiliser Deal Amid Canada Trade Dispute
 UK Borrowing Hits £18.3bn Ahead of Budget
 Iran Rejects Claims of Shift in US Talks
 Chinese Hybrid Car Surge Raises EU Auto Industry Concerns
 Tony Blair Calls for Britain to Rejoin EU Within a Decade
 UK Trade Losses Grow Without EU Product Deal
 Should Savers Lock Into 5.25% Fixed Rates?
 UK Diesel Prices Hit Record High Amid Iran Conflict
 Ukraine Faces $45m Hourly Cost From Missile Alerts
 Poundland Rescue Bid Could Protect 11,000 Jobs
 UK house price growth slows as mortgage rates rise
 UK borrowing costs surge as global bond sell-off deepens
 French Debt Fears Put Euro Markets Under Pressure
 UK Assures Public Over Diesel Supply
 UK Diesel Reaches £2 as Inflation Surges Across Europe
 Minister Rejects Fears of UK Diesel Shortage
 London Council Warns of 150% Council Tax Rise
 UK Doubles Steel Tariffs to 50% to Protect Domestic Plants
 Albanese Rejects Gas Export Tax Push
 US Awaits Iran Reply on New Ceasefire Proposal
 Kevin Warsh sworn in as Fed chair amid economic backlash
 UK Pushes for New EU Goods Trade Deal
 Albanese Defends Tax Reforms Amid Emotional Speech
 Victoria Labor Launches Apprenticeship Expansion Plan
 UK rejects EV charging VAT cut amid Treasury clash
 Nationwide Faces Governance Scrutiny Ahead of AGM
 Hungary Targets Oligarchs with Proposed Landmark Wealth Tax
 Weight-Loss Drugs Transform Fashion Shopping Habits
 Trump Refuses to Sign Housing Bill, But Law Takes Effect
 Canada to Match Trump’s 50% Tariffs Dollar for Dollar
 Firms on both sides fear damage from US-Canada trade war
 US CEOs Earn 614 Times More Than Workers
 Europe Faces Winter Gas Supply Anxiety
 Reform Faces Fresh Financial Controversy
 UK Cost Squeeze Deepens as Mortgages and Gas Rise
 Swedish Mining Push Puts Sami Land Rights Under Pressure
 Billionaire Chris Rokos poised to leave UK
 JPMorgan Boss Warns Against UK Bank Tax Rise
 John Lewis Losses Widen to £124m as Confidence Falls
 Saudi Arabia Shuts Oil Pipeline After Drone Attack
 North Sea Firms Urge Early End to Windfall Tax
 Trump Threatens EU With Tariffs Over Canada Proposal
 UK Productivity Improves as Bank Weighs Interest Rates
 Trump Threatens EU Over Canada Partnership Proposal
 Tom Watson Takes Senior Role at Palantir
 UK Rent Gap Puts Low-Income Families Under Pressure
 Reform UK Faces Internal Debate Over £72m Spending
 Calls Grow to Expand UK National Wealth Fund
 Trump gives Xi red-carpet welcome as trade truce extends
 AO Acquires Jessops in Camera Retail Expansion
 Xi urges Trump to avoid US-China military conflict
 Burnham Opens Door to Possible UK Return to EU
 Healey urged to act as UK energy bills rise 4%
 Boots Sale Nears as Weston Family Eyes $9bn Deal
 Badenoch Raises Prospect of 2027 UK Election
 DOJ Declines to Reopen Powell Renovation Probe
 North Sea Strike Threatens UK Fuel Supplies
 UK Weighs Chinese Car Tariffs Amid EU Trade Push
 BT Agrees £400m TalkTalk Rescue Deal
 UK house prices stall as mortgage costs rise
 Shell Refineries Set for Record Refining Profits