
Published: 17 September 2026. The English Chronicle Desk. The English Chronicle Online
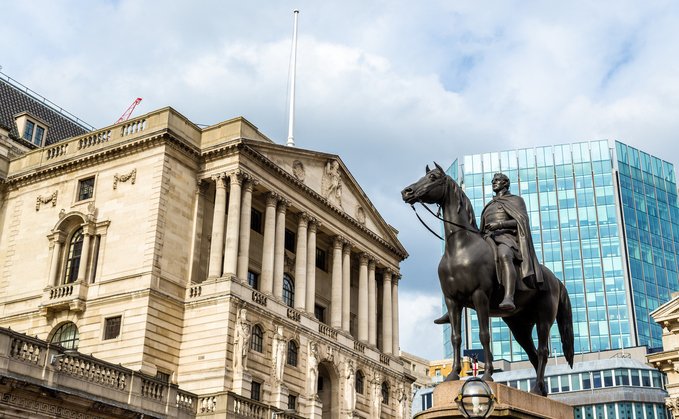
Britain’s economic picture has become more complicated ahead of the Bank of England’s latest interest-rate decision, with new analysis suggesting that the UK economy may have been more productive than previously estimated even as inflationary pressures and a weakening labour market create difficult choices for policymakers.
The Bank of England’s Monetary Policy Committee was due to announce its latest decision on Thursday, 17 September, with Bank Rate standing at 3.75% after the previous meeting. At its July meeting, six members voted to keep the rate unchanged while three preferred a quarter-point increase to 4%. The latest decision therefore comes against a backdrop of disagreement over how strongly monetary policy needs to respond to inflation.
The central issue facing policymakers is the balance between persistent price pressures and signs that economic activity and employment remain under strain. The Bank’s mandate is to maintain price stability around the government’s 2% inflation target, but higher interest rates can also increase borrowing costs for households and businesses.
The Bank’s latest published figures before Thursday’s decision showed CPI inflation at 3.1%, above the 2% target. The central bank has previously warned that higher energy prices could push inflation higher later in the year, while also acknowledging that the effects of tighter financial conditions and a loosening labour market could restrain economic activity.
Against that difficult backdrop, fresh discussion about UK productivity provides a potentially more positive element to the economic picture. Productivity measures how efficiently an economy produces goods and services from the labour and other resources available to it. Stronger productivity can allow an economy to expand without necessarily creating the same inflationary pressures that can arise when growth is driven primarily by increased demand.
The latest reassessment is significant because productivity has been one of the UK’s longstanding economic challenges. Official and independent assessments have repeatedly pointed to weak productivity growth since the global financial crisis. The Office for Budget Responsibility has previously noted that revisions to GDP and hours-worked data can materially change the picture of UK productivity, highlighting the uncertainty surrounding estimates.
The productivity debate is particularly important for the Bank of England because estimates of how much the economy can produce without generating persistent inflation influence monetary policy. If the economy has greater productive capacity than previously estimated, policymakers may have more room to accommodate economic activity. That does not automatically determine an interest-rate decision, however, because the MPC must consider a wide range of indicators, including inflation, wages, employment, demand and financial conditions.
The latest economic discussion comes after a period in which the UK economy has produced mixed signals. Recent output data have provided some evidence of growth, while employment indicators have remained weaker. In the live market coverage, analysts pointed to falling payroll employment, subdued real wage growth and vacancies at relatively low levels as signs of pressure in the labour market.
At the same time, stronger-than-expected economic growth in July complicated the picture. The Guardian’s live coverage reported that July growth had exceeded expectations, with investment associated with artificial intelligence, construction and manufacturing among the factors being discussed. The combination of stronger output and weaker employment creates uncertainty about the underlying strength of the economy.
For the Bank, the challenge is not simply whether the economy is growing. Policymakers must assess whether growth is sustainable and whether it is consistent with inflation returning to target over time.
The previous Bank of England meeting illustrated how divided those considerations can become. In July, three members of the nine-person MPC voted for a rate increase, while the remaining six supported holding Bank Rate at 3.75%. The decision followed a period in which inflation had fallen to 2.6%, although the Bank expected price pressures to rise later in the year because of higher energy costs.
Since then, inflation has moved further above target. The Bank’s current public information lists inflation at 3.1%, compared with its 2% target. The central bank has also continued to emphasise the uncertainty created by energy prices and their effect on household bills and business costs.
The interest-rate decision is also taking place alongside a separate debate about quantitative tightening, or QT. This is the process through which the Bank reduces its holdings of government bonds accumulated during earlier rounds of quantitative easing.
The Bank has been gradually reducing its stock of government bonds. At the end of July, the stock held for monetary-policy purposes stood at £491bn. The pace and composition of further bond sales have become a subject of political and financial debate because changes in the supply of government bonds can influence market prices and yields.
When bond prices fall, yields generally rise. Higher government bond yields can feed into borrowing costs across the economy, although the relationship between the Bank’s bond operations and market rates is influenced by many other factors.
The decision over QT is therefore being watched alongside Bank Rate. Economists cited in the live coverage expected the Bank could slow the pace of bond sales, while some debate has centred on whether sales of longer-dated government bonds should be adjusted.
The issue has also attracted criticism because the Bank’s bond-buying and subsequent bond-selling programmes have generated substantial financial losses and gains over different periods. The treatment of those costs has prompted debate about the relationship between monetary policy and public finances.
The Bank has maintained that its monetary-policy operations should be assessed over the longer term rather than by focusing on individual years. Critics, however, have argued that near-term cash flows can have consequences for government finances and therefore deserve greater scrutiny.
The broader financial environment is also being shaped by decisions outside Britain. The US Federal Reserve raised its interest rate on 16 September, according to reporting cited in the live coverage, adding another international dimension to the Bank of England’s deliberations.
Central banks do not have to follow one another’s decisions. Each monetary-policy committee responds to conditions in its own economy. Nevertheless, major changes in US interest rates can influence financial markets, exchange rates and global borrowing conditions, which can become relevant to UK policymakers.
For British households, the consequences of the Bank’s decision are likely to be felt most directly through borrowing and saving costs. Bank Rate influences the rates offered by financial institutions, although the interest rates paid by consumers and businesses also depend on the type of financial product, lender risk and broader market conditions. The Bank itself explains that higher Bank Rate generally increases borrowing costs while affecting the returns available to savers.
Businesses are similarly affected. Higher financing costs can make investment more expensive, while lower rates can reduce the cost of borrowing for expansion and investment. This means the Bank must consider how monetary policy affects both current demand and the economy’s longer-term productive capacity.
Productivity is central to that longer-term question. A sustained improvement in output per hour could support stronger economic growth without requiring an equivalent increase in labour input. It could also improve the potential for real wage growth and strengthen the government’s tax base over time.
But economists continue to stress that productivity estimates are uncertain and can be revised as new information becomes available. The OBR has previously highlighted the difficulty of forecasting productivity and noted that different datasets can produce different assessments of the UK’s recent performance. Its November 2025 forecast, for example, revised down its estimate of medium-term underlying productivity growth to 1%, illustrating how assessments can change as evidence develops.
The latest discussion should therefore be viewed as an update to the understanding of Britain’s economic capacity rather than evidence that the country’s long-running productivity problem has disappeared.
The Bank’s decision on Thursday was consequently being watched for more than the headline interest-rate figure. Investors, businesses and households were also looking for indications of how policymakers viewed inflation, economic growth, labour-market conditions and the future path of quantitative tightening.
With inflation still above target, employment showing signs of weakness and productivity estimates evolving, the economic picture remains unusually complex. Stronger-than-expected output and potentially better productivity data offer some encouragement, but they do not remove the pressures created by elevated prices and higher financing costs.
The latest developments underline the difficulty facing the Bank of England as it attempts to bring inflation back towards 2% without placing unnecessary pressure on an economy that is already showing signs of strain. The September meeting therefore represents another important point in a monetary-policy cycle in which policymakers must weigh competing signals rather than rely on a single measure of economic health.
Whatever the immediate decision, the debate over Britain’s productivity performance is likely to remain important. If the economy can produce more with the resources already available, that could influence expectations for future growth, wages, public finances and monetary policy. But determining how durable that improvement is will require further data and continued revisions to the UK’s economic statistics.
Related News:
 Oil nears $100 as Saudi attacks shake markets
 Thames Water Revises Oxfordshire Mega-Reservoir Plan
 Next Raises Profit Forecast After Strong Summer Sales
 UK rejects EV charging VAT cut amid Treasury clash
 Pubs and Hotels Face Business Rates Reform Review
 Firms on both sides fear damage from US-Canada trade war
 UK Cost Squeeze Deepens as Mortgages and Gas Rise
 Spire Healthcare Agrees £1bn Takeover by Toscafund
 UK House Prices Fall as Mortgage Rates Rise
 Billionaire Chris Rokos poised to leave UK
 JPMorgan Boss Warns Against UK Bank Tax Rise
 John Lewis Losses Widen to £124m as Confidence Falls
 Oil Prices Surge as Saudi Pipeline Closure Deepens Crisis
 UK State Pension Set to Rise 3.9% as Triple Lock Holds
 UK Parents Cut School Uniform Costs as Prices Rise
 UK Pay Growth Slows to 3.9% as Rate Decision Nears
 Bank Urged to Slow Bond Sales as UK Costs Rise
 UK Inflation Hits 3.1% as Household Pressure Grows
 Entain Plans 400 Job Cuts After Profit Update
 Wealthy Britons Flee Gulf War but Avoid UK Taxes
 UK Wage Growth Slows as Jobs Market Holds Firm
 Europe EV Demand Surges as Fuel Prices Rise
 BBC News Faces Deep Cuts in 2,000 Job Plan
 New UK advice scheme to boost savings and investing
 Reeves Fights to Keep Treasury Role Amid Labour Turmoil
 UK firms accused of ‘AI washing’ boom
 EasyJet Takeover Sparks Fears Over Passengers’ Future
 Shein targets $27bn valuation in Hong Kong debut
 US CEOs Earn 614 Times More Than Workers
 UK Risks Falling Behind in AI Race
 Europe Faces Winter Gas Supply Anxiety
 UK Households Could Save £173 on Fixed Energy Deals
 Burnham Faces Mounting Budget Challenges
 Dutch Bank Moves 86 Tonnes of Gold to London
 McLaren to Create 1,000 UK Jobs in £450m Investment
 Nats Boss Summoned as UK Flight Chaos Continues
 UK Retailers Accused of Breaking Refund Laws
 Farage Threatens Union Funding Ban Over Reform Donations
 Fashion Firms Urge UK-Made NHS and Army Uniforms
 North Sea Firms Urge Early End to Windfall Tax
 JLR Eyes NATO Market With New Defender Military Vehicle
 UK Youth Jobs Gap Reveals Deep Regional Divide
 Mayors Could Gain New Powers Over UK Water Firms
 Mayors Could Gain Greater Powers Over Water Firms
 Horse Hill Oil Site Sold as New Drilling Bid Emerges
 Anthropic Backs $31.9bn Queensland Data Centre
 Horse Hill Oil Site Sold for £1m as Drilling Bid Returns
 Tories Press Healey Over Tax Rises Ahead of Budget
 Trump Threatens EU With Tariffs Over Canada Proposal
 How to Exit Your Broadband Contract Without Paying Exit Fees
 Ed Davey Urges Government to Block Elon Musk’s Tesla from Supplying UK Home Energy
 UK Could Generate Nearly £2bn Annually by Taxing SUVs, New Study Reveals
 Jaguar Land Rover Extends Production Halt Following Cyber-Attack
 British AI Startup Outshines Human Forecasters in Global Prediction Contest
 Royal Mail Owner Acquires Stake in Collect+ and Launches High Street Rebrand
 NHS May Pay 25% More for Medicines Amid US Drug Talks
 North Sea oil workers must lose weight or face job loss
 UK Taskforce Unveils Plan to Streamline Nuclear Reactor Rules
 AI job losses UK: Britain faces sharper employment shock
 UK New Car Discounts Near £6,000 as Prices Are Slashed
 UK Doubles Steel Tariffs to 50% to Protect Domestic Plants
 Student Loan Interest May Rise Despite 6% Cap
 Reform UK funding: mystery billionaire revealed
 Albanese Rejects Gas Export Tax Push
 UK Pushes for New EU Goods Trade Deal
 Weight-Loss Drugs Transform Fashion Shopping Habits
 Labour MPs Urge Burnham to Revive UK Aid Target
 Weight-Loss Drugs Offer Food Savings Mainly to High Earners
 Canada to Match Trump’s 50% Tariffs Dollar for Dollar
 London Launches First Self-Driving Taxis
 Trump Hardens Canada Trade Stance as Talks Stall
 UK Subsidence Claims Surge After Record-Breaking Summer
 Reform Faces Fresh Financial Controversy
 Swedish Mining Push Puts Sami Land Rights Under Pressure
 Iceland to Open First UK High Street Store in Falklands
 AI CEOs Call for Slower Development
 Heathrow Expansion Faces New Climate Conditions Over CO₂
 UK Heatwaves Set to Worsen Pothole Damage, RAC Warns
 Enhertu Approved for Eligible Breast Cancer Patients in England
 OpenAI Reveals Six Cases of Concerning AI Behaviour