
Published: 21 October 2026. The English Chronicle Desk. The English Chronicle Online
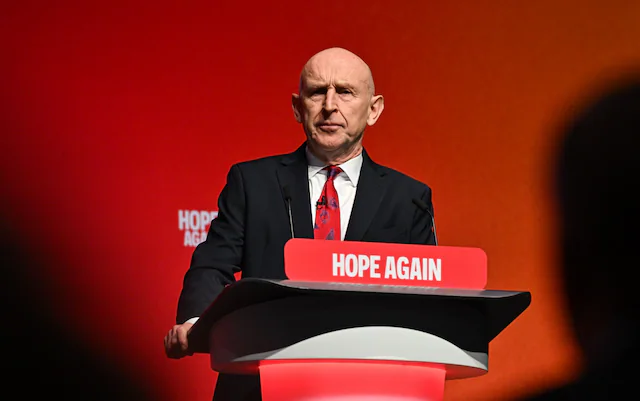
The UK government’s budget deficit widened to £24.5 billion in September, exceeding economists’ expectations as rising inflation drove up the cost of servicing public debt and increased pressure on Chancellor John Healey ahead of his first budget next week. Official figures revealed that the government paid £10.9 billion in interest on its debt during the month, the highest September total since records began. The figures underline the financial challenges facing the government as it attempts to maintain control of public spending, support economic growth and respond to the rising cost of living amid the economic consequences of the conflict involving Iran.
The latest data presents a difficult backdrop for Healey, who is preparing to set out the government’s financial priorities at a time when borrowing costs remain elevated and energy prices have pushed inflation higher. With public debt reaching an estimated £3 trillion, the government faces growing pressure to balance its spending commitments against the need to maintain credible fiscal rules and reassure financial markets about the sustainability of the country’s public finances.
The Office for National Statistics reported that public sector net borrowing reached £24.5 billion in September, up from £17 billion in August. The latest monthly deficit was also £1.9 billion higher than the independent Office for Budget Responsibility had forecast. The difference between the actual figure and the forecast highlights the difficulty of predicting government finances when inflation, energy prices and debt interest costs are changing rapidly.
The increase was driven in significant part by the rising cost of servicing government debt. Interest payments reached £10.9 billion in September, making it the most expensive September on record for debt interest and only the eighth time that monthly payments have exceeded £10 billion. The figure illustrates how changes in inflation can affect the government’s finances even when ministers have not introduced new spending programmes.
A key factor is the structure of some UK government bonds, whose payments are linked to the Retail Prices Index, or RPI, a measure of inflation. When RPI rises, the amount the government owes on these inflation-linked securities can increase, pushing up the cost of servicing its debt. The recent increase in inflation, partly driven by higher energy prices associated with the Iran conflict, has therefore created an additional burden for the Treasury.
The ONS estimated that the recent rise in inflation added £4 billion to government debt interest costs in September alone. That increase demonstrates how an international crisis can affect public finances well beyond the immediate cost of energy. Higher oil and gas prices raise expenses for households and businesses, while the resulting inflation can also increase the government’s borrowing costs through its existing debt arrangements.
For the Treasury, the timing is particularly challenging. Healey is due to present his first budget next Wednesday, when he will be expected to explain how the government intends to manage public spending, support the economy and maintain its commitments on taxation and borrowing. The latest figures narrow the room for manoeuvre and could complicate decisions over how much financial support can be offered to households and public services.
The government’s total debt is estimated to have reached £3 trillion for the first time. Although the headline figure is substantial, debt levels are also assessed relative to the size of the economy, which provides a broader indication of the country’s capacity to manage its obligations. On this measure, public debt fell to 94% of gross domestic product, compared with 95% a year earlier.
The decline in the debt-to-GDP ratio offers a limited positive signal, suggesting that the economy’s size has grown relative to the stock of debt over the period. However, the ratio remains high, and the government must still finance its existing obligations while covering the cost of public services and meeting future spending needs. A large debt stock can leave public finances vulnerable to changes in interest rates, inflation and economic growth.
The September borrowing figures also need to be considered within the wider financial year. Public sector net borrowing reached £97.8 billion in the financial year so far, according to the ONS. That was £4.4 billion lower than during the corresponding period last year, indicating some improvement compared with the previous year. Nevertheless, borrowing remained £6 billion above the level forecast by the Office for Budget Responsibility.
The combination of lower borrowing than last year but a larger-than-expected deficit compared with forecasts presents a mixed picture. It suggests that the government has made some progress in containing the overall pace of borrowing, while also showing that unexpected developments can quickly undermine its financial plans. The recent rise in debt interest is particularly significant because it can absorb money that might otherwise be available for public services or investment.
Healey has repeatedly emphasised his determination to comply with the fiscal rules established by his predecessor, Rachel Reeves. Such rules are intended to provide a framework for managing public debt and borrowing over time, helping the government demonstrate that its spending and taxation plans are financially sustainable. They also influence how much flexibility the chancellor has when considering new policies.
However, the pressure created by higher debt interest and a weaker-than-expected monthly borrowing position has raised questions about the size of the financial buffer, commonly known as fiscal headroom, that Healey will retain. Headroom represents the margin between the government’s projected finances and the limits imposed by its fiscal rules. A larger buffer provides some protection if economic conditions deteriorate or forecasts turn out to be too optimistic.
Healey is widely expected to accept a smaller margin than the £24 billion buffer Reeves had established at the time of her spring forecast in March. Reducing that cushion could allow the government to accommodate some immediate financial priorities, but it would also leave less room to absorb future shocks. If inflation remains higher than anticipated, growth weakens or borrowing costs rise further, the government could find itself under renewed pressure to revise its plans.
The issue is particularly important because the economic outlook remains uncertain. Higher energy prices have increased inflationary pressures, while concerns about the cost of living continue to weigh on households. If businesses face sustained increases in transport and production costs, they may pass some of those expenses on to consumers, potentially prolonging inflation. The Bank of England may also need to keep monetary policy tighter than otherwise expected, which could affect economic activity and the cost of financing government debt.
At the same time, the relationship between inflation and public finances is complicated. Higher prices can increase government revenues because taxes collected on spending, earnings and business activity may rise in cash terms. Inflation can also increase some tax receipts as nominal wages and prices move higher. However, these potential gains do not necessarily translate into a stronger financial position because government spending obligations and debt interest costs can rise at the same time.
The latest figures illustrate this tension. Although higher inflation may boost certain revenues, the increase in debt interest has already created a substantial additional cost for the Treasury. Public services may also face pressure when departmental budgets do not rise in line with the prices of the goods, equipment, contracts and services they need to purchase. In real terms, fixed budgets can buy less, potentially making it harder for departments to maintain existing services or meet rising demand.
These pressures could complicate decisions on healthcare, education, transport, local government and other public services. If the government chooses to protect departmental budgets against inflation, it may have less flexibility elsewhere. If it limits spending increases, public bodies could face difficult choices about priorities, efficiency and service delivery. The budget will therefore be closely watched for indications of how Healey intends to distribute limited resources.
Financial markets will also be paying attention to the government’s approach. Investors assess not only the immediate borrowing figure but also whether the government’s longer-term plans appear credible. A clear strategy for controlling borrowing and supporting sustainable economic growth could help maintain confidence, while persistent forecast shortfalls or repeated changes to fiscal plans could increase uncertainty.
Nevertheless, the September figures do not by themselves determine the government’s overall financial position. Monthly borrowing can fluctuate because of changes in tax receipts, spending patterns, debt interest and other factors. The performance across the financial year, together with updated forecasts for growth, inflation and government revenue, will be important in assessing the longer-term outlook.

The central challenge for Healey is to respond to immediate economic pressures without sacrificing the government’s ability to manage public debt over time. He must consider the needs of households affected by higher prices, the demands of public services and the importance of maintaining a credible fiscal framework. Those objectives may conflict, particularly if energy costs remain elevated and the economy fails to generate stronger growth.
As the budget approaches, the latest borrowing figures have made the choices facing the Treasury more difficult. The record September debt interest bill demonstrates how quickly inflation can affect the public finances, while the higher-than-forecast deficit highlights the risks of planning around uncertain economic conditions. With total government debt estimated at £3 trillion, Healey will need to demonstrate how the government intends to contain borrowing, protect essential priorities and preserve enough financial flexibility to respond to future shocks.
Related News:
 Thinktank Calls for Abolition of UK State Pension
 MPs Defend UK Economic Watchdog Against Critics
 Informa Agrees £2.24bn Deal to Buy Clarion
 IFS Warns UK Budget Faces £35bn Spending Gap
IMF Raises UK Growth Forecast Ahead of Healey’s Budget
 Business Chief Urges Burnham to Fix Brexit Damage
 BBC News Faces Deep Cuts in 2,000 Job Plan
 Reeves Fights to Keep Treasury Role Amid Labour Turmoil
 Burnham Faces Mounting Budget Challenges
 UK House Prices Fall as Mortgage Rates Rise
 Oil nears $100 as Saudi attacks shake markets
 Thames Water Revises Oxfordshire Mega-Reservoir Plan
 UK Pay Growth Slows to 3.9% as Rate Decision Nears
 Bank Urged to Slow Bond Sales as UK Costs Rise
 UK Inflation Hits 3.1% as Household Pressure Grows
 UK Retail Sales Rebound as Consumers Spend More
 UK Borrowing Hits £18.3bn Ahead of Budget
 Tony Blair Calls for Britain to Rejoin EU Within a Decade
 UK Trade Losses Grow Without EU Product Deal
 Saudi intercepts Houthi missiles as oil fears grow
 Should Savers Lock Into 5.25% Fixed Rates?
 UK Diesel Prices Hit Record High Amid Iran Conflict
 Poundland Rescue Bid Could Protect 11,000 Jobs
 UK house price growth slows as mortgage rates rise
 UK borrowing costs surge as global bond sell-off deepens
 UK Assures Public Over Diesel Supply
 UK Diesel Reaches £2 as Inflation Surges Across Europe
 Minister Rejects Fears of UK Diesel Shortage
 London Council Warns of 150% Council Tax Rise
 EU-China Talks Target Surge in Hybrid Car Imports
 IMF Warns Governments Over Rising Debt Burdens
 Google Maps Brings Live Fuel Prices to UK Drivers
 Ministers Push ATO to Reconsider Credit Card Ban
 Australia Delays Tax Credit Card Payment Ban After Backlash
 France Faces Debt Crisis as Protests and Markets Clash
 Labour Fears Budget Will Fail to Lift Living Standards
 UK Van Drivers Face £2.5bn Diesel Cost Surge
 IMF Warns Global Economy Is Nearing Its Limits
 Healey Plans £1bn Online Marketplace Tax Crackdown
 UK Could Rejoin EU Through a Switzerland Plus Deal
 UK Unemployment Falls to 4.7% as Vacancies Decline
 UK Doubles Steel Tariffs to 50% to Protect Domestic Plants
 UK Pushes for New EU Goods Trade Deal
 UK rejects EV charging VAT cut amid Treasury clash
 Labour MPs Urge Burnham to Revive UK Aid Target
 Europe Faces Winter Gas Supply Anxiety
 UK Households Could Save £173 on Fixed Energy Deals
 Trump Hardens Canada Trade Stance as Talks Stall
 Reform Faces Fresh Financial Controversy
 UK Cost Squeeze Deepens as Mortgages and Gas Rise
 Billionaire Chris Rokos poised to leave UK
 JPMorgan Boss Warns Against UK Bank Tax Rise
 John Lewis Losses Widen to £124m as Confidence Falls
 North Sea Firms Urge Early End to Windfall Tax
 Trump Threatens EU With Tariffs Over Canada Proposal
 UK Productivity Improves as Bank Weighs Interest Rates
 Trump Threatens EU Over Canada Partnership Proposal
 Japan Raises Rates to 31-Year High
 UK Rent Gap Puts Low-Income Families Under Pressure
 Reform UK Faces Internal Debate Over £72m Spending
 Calls Grow to Expand UK National Wealth Fund
 Trump Eyes Major Belarus Fertiliser Deal Amid Canada Trade Dispute
 Iran Rejects Claims of Shift in US Talks
 Chinese Hybrid Car Surge Raises EU Auto Industry Concerns
 AO Acquires Jessops in Camera Retail Expansion
 Beaverbrooks Boss Calls for Relief on Business Costs
 Burnham Opens Door to Possible UK Return to EU
 Healey urged to act as UK energy bills rise 4%
 Boots Sale Nears as Weston Family Eyes $9bn Deal
 French Debt Fears Put Euro Markets Under Pressure
 Badenoch Raises Prospect of 2027 UK Election
 North Sea Strike Threatens UK Fuel Supplies
 UK Weighs Chinese Car Tariffs Amid EU Trade Push
 BT Agrees £400m TalkTalk Rescue Deal
 UK house prices stall as mortgage costs rise
 Tesco Raises Profit Forecast as Consumer Confidence Holds
 Oil Shock Sends Markets Lower as Middle East Risks Grow
 Hall and Woodford Win Nobel Economics Prize
 UK Plans Higher Training Costs for Older Apprentices
 UK Inflation Hits 3.5% as Middle East War Drives Fuel Costs