
Published: 15 October 2026. The English Chronicle Desk. The English Chronicle Online.
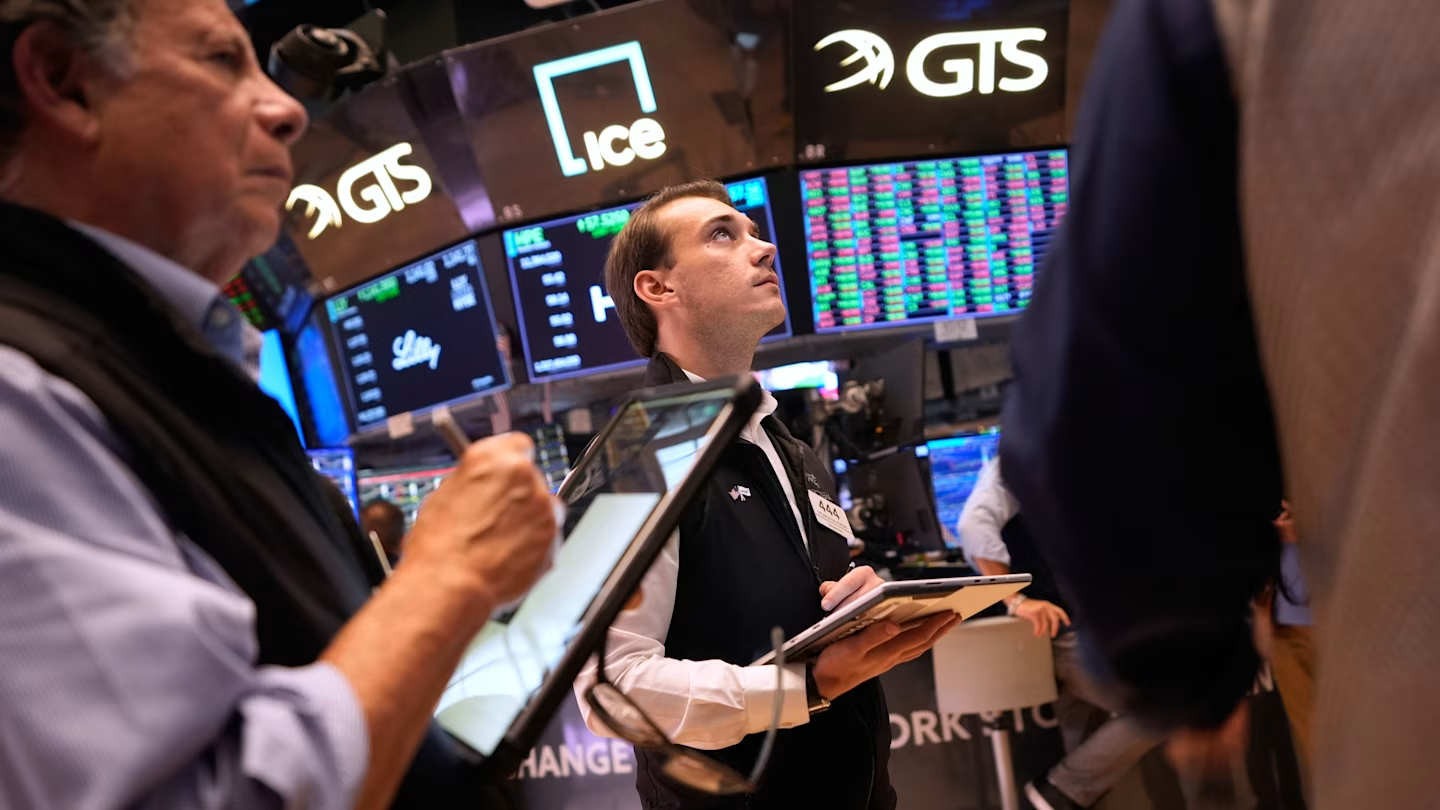
Global financial markets came under renewed pressure on Thursday as a sharp sell-off in technology shares intensified concerns about rising US inflation, potential interest rate increases and the growing debt associated with the artificial intelligence industry. Major technology companies and semiconductor manufacturers suffered significant losses across Asia, while European equities weakened and US stock futures pointed towards further declines. The latest turmoil has raised questions about whether investor enthusiasm for artificial intelligence has pushed valuations too high and whether a correction could threaten broader financial stability.
South Korea’s technology-heavy stock market was among the hardest hit. The benchmark Kospi index fell 8.1% to its lowest closing level in six months, as investors rushed to reduce their exposure to semiconductor manufacturers and other companies closely associated with the global AI investment boom. The scale of the decline triggered market circuit breakers, temporarily halting trading at various points in an attempt to contain extreme volatility.
Major chipmakers suffered substantial losses. SK Hynix shares plunged by nearly 11%, while Samsung Electronics fell approximately 9.5%. Both companies occupy important positions in the global semiconductor supply chain, particularly in memory chips used in data centres, computers and AI systems. Their declines reflected concerns that even businesses benefiting from growing demand for advanced computing infrastructure could face pressure if financing costs rise and investors reassess the value of future growth.
Japan also experienced a steep downturn. The Nikkei 225 index dropped 4.9% on Thursday, following significant losses among technology-related companies. Memory chip manufacturer Kioxia fell 11%, while SoftBank, a major investor in OpenAI, the company behind ChatGPT, declined by 10%. The movements illustrated how closely Japanese markets have become linked to global expectations surrounding AI development, semiconductor demand and the future profitability of technology investments.
The latest declines followed a difficult session on Wall Street. On Wednesday, the Nasdaq Composite fell 1.9%, while the S&P 500 lost 1.1%, marking the latter index’s worst performance since July. The weakness continued to influence trading across international markets as investors reassessed the economic outlook and the possibility that central banks might maintain restrictive monetary policies for longer than previously expected.
At the centre of the latest market anxiety is a stronger-than-anticipated increase in US consumer prices. Inflation reached 3.7% in September, according to the figures cited in market reports, marking the fastest annual increase since the consumer price index reached 4.2% in May. The latest reading has complicated expectations for monetary policy at a time when investors had been hoping for more favourable conditions for businesses and financial markets.
Higher inflation matters because it can limit the Federal Reserve’s ability to reduce interest rates. When prices rise persistently, policymakers may decide to keep borrowing costs elevated or increase them further to prevent inflationary pressures from becoming entrenched. Such decisions can affect everything from mortgage payments and business loans to corporate investment and the valuation of shares.
Technology companies are particularly sensitive to changes in interest rates because much of their market value depends on expectations about future earnings. When borrowing becomes more expensive, businesses may delay expansion, reduce spending or face higher costs when financing new projects. Investors may also apply lower valuations to companies whose profits are expected to materialise years into the future.
The latest inflation figures have therefore forced traders to reconsider the possibility of further monetary tightening. Some market participants have reportedly begun pricing in another US interest rate increase as early as the end of October. Although market expectations can change quickly and do not guarantee a particular policy decision, the prospect of higher rates has added to the pressure on technology shares.
Analysts at Deutsche Bank described the previous 24 hours as exceptionally turbulent, pointing to the combination of stronger US consumer price data and mounting concerns about investments linked to artificial intelligence. Their assessment highlighted how economic uncertainty and sector-specific fears can reinforce one another, creating a difficult environment for investors attempting to distinguish temporary volatility from deeper financial risks.
Another important aspect of the inflation report was that the increase appeared to extend beyond energy prices. Geopolitical tensions, including the economic consequences of the US war on Iran, have contributed to concerns about fuel costs and international supply chains. However, the latest figures reportedly showed broader increases across the consumer price basket, suggesting that inflationary pressure could be more widespread than a temporary rise in energy prices alone.
This distinction is significant for central banks. If inflation is concentrated in a narrow group of goods, policymakers may be able to look through some of the immediate price movements. When price increases spread across multiple categories, however, the risk of persistent inflation becomes more difficult to dismiss. That can make monetary authorities more cautious about lowering borrowing costs.
Alongside inflation, concerns about debt in the artificial intelligence industry have become a major source of unease. The rapid expansion of AI has encouraged technology companies, infrastructure providers and investors to commit enormous sums to data centres, advanced chips, cloud computing and related facilities. Much of this investment is based on expectations that demand for AI services will continue to grow and eventually generate substantial profits.
However, building the infrastructure needed to support AI requires significant upfront expenditure. Data centres need specialised equipment, powerful processors, cooling systems, electricity supplies and extensive network infrastructure. Companies must often make these investments well before the long-term revenue from their AI services becomes clear.
If demand fails to meet expectations, or if competition reduces the prices companies can charge for AI services, some investments may take longer to generate acceptable returns. Businesses that have borrowed heavily to fund expansion could face additional pressure if interest rates remain high. Investors are increasingly examining whether the potential future earnings from AI can justify the costs and financial commitments involved.
The International Monetary Fund has already warned that a sharp correction in AI-related share prices could pose a risk to global financial stability. Its concerns extend beyond individual technology companies because losses can spread through investment funds, pension portfolios, lenders and other financial institutions with substantial exposure to the sector.
A significant decline in technology valuations could also affect household wealth. Investors who hold technology shares directly or through retirement savings and other investment products may see the value of their portfolios fall. If financial institutions become more cautious, businesses outside the technology industry could also encounter tighter access to funding.
The IMF’s warning has intensified scrutiny of the relationship between the AI boom and the wider financial system. While artificial intelligence has the potential to improve productivity and create new commercial opportunities, the speed and scale of investment have raised questions about whether market expectations have become excessively optimistic.
Asian markets may be particularly exposed to a correction because of their concentration in semiconductor manufacturing and related technology businesses. South Korea is home to major memory chip producers, while Taiwan plays a central role in advanced semiconductor production. Japan also has important companies involved in chip manufacturing, equipment and technology investment.
Taiwan’s TSMC, one of the world’s leading semiconductor manufacturers and Asia’s most valuable company, fell 2% during Thursday’s trading despite reporting its sixth consecutive quarter of profits. The decline illustrated how strong corporate earnings may not always be enough to protect shares when investors become concerned about valuations, economic conditions and the broader outlook for the sector.
China’s markets also weakened. The CSI 300 index fell by as much as 2.4%, reaching its lowest level since August 2025. The decline added to the regional pressure as investors considered the implications of weaker technology sentiment for manufacturing, investment and international demand.
European equities opened lower as the sell-off spread westwards. The Stoxx Europe 600 fell 0.4% at the start of trading, while the UK’s FTSE 100 declined 0.06%. France’s CAC 40 slipped 0.19%, Spain’s Ibex dropped 0.17% and Germany’s DAX fell 0.53%.
Although the losses were generally smaller than those recorded in South Korea and Japan, the declines demonstrated that concerns about US inflation and AI-related investments were influencing markets well beyond the technology sector. European investors also face questions about economic growth, corporate profitability and the consequences of higher global borrowing costs.
In the United States, Nasdaq 100 futures fell 1%, signalling expectations of further weakness among major technology companies when regular trading resumed. Futures movements are not a guarantee of how markets will ultimately perform, but they indicated that investors remained cautious after Wednesday’s losses.
For businesses, the combination of rising inflation and uncertain technology valuations creates a challenging environment. Companies considering new investments must weigh the potential benefits of adopting AI against the costs of equipment, financing and implementation. If borrowing costs increase, some projects may become less attractive, particularly where expected returns are uncertain.
At the same time, a sustained decline in technology shares would not necessarily mean that artificial intelligence itself has lost its economic value. The technology may continue to expand across industries even if investors revise their expectations about which companies will benefit most, how quickly profits will emerge and how much they are willing to pay for future growth.
The central question for financial markets is whether the latest declines represent a temporary adjustment or the beginning of a more prolonged reassessment of AI-related investments. Much will depend on forthcoming inflation data, Federal Reserve decisions, corporate earnings and evidence about whether spending on AI infrastructure is producing sustainable returns.
Investors will also be watching developments in global energy markets and geopolitical tensions, which could influence inflation and the direction of interest rates. A further increase in prices could complicate efforts to stabilise financial conditions, while signs of easing inflation might help restore confidence.
For now, the simultaneous pressure on Asian technology shares, weaker European markets and declining US futures underscores the interconnected nature of the global financial system. A change in expectations about US monetary policy can quickly influence borrowing costs, investment decisions and share prices across continents.
The latest sell-off serves as a reminder that even industries associated with transformative innovation are not immune to conventional economic pressures. Artificial intelligence may reshape business and productivity, but the companies financing its expansion remain exposed to interest rates, debt obligations, competition and the possibility that investor expectations have moved ahead of financial reality.
As markets navigate the latest uncertainty, investors face the difficult task of balancing the long-term potential of AI against the immediate risks posed by inflation, expensive financing and elevated valuations. Until those concerns become clearer, volatility is likely to remain an important feature of global technology markets.
Related News:
 Firmus Abandons Major ASX Listing Amid Investor Doubts
 EU Caps Chinese Hybrid Car Imports at 350,000
 Chinese Hybrid Car Surge Raises EU Auto Industry Concerns
 Bank Chief Calls for Power to Intervene in AI
 Asos Investigates Hack Claims After Customer Alerts
 UK firms accused of ‘AI washing’ boom
 UK Risks Falling Behind in AI Race
 Billionaire Chris Rokos poised to leave UK
 Oil nears $100 as Saudi attacks shake markets
 JPMorgan Boss Warns Against UK Bank Tax Rise
 AI CEOs Call for Slower Development
 Thames Water Revises Oxfordshire Mega-Reservoir Plan
 UK Productivity Improves as Bank Weighs Interest Rates
 Nvidia chief rejects AI extinction fears
 Trump gives Xi red-carpet welcome as trade truce extends
 UK Trade Losses Grow Without EU Product Deal
 TalkTalk Races to Sell Arms as Administration Looms
 Why Americans Feel Ripped Off by Rising Prices
 Poundland Rescue Bid Could Protect 11,000 Jobs
 Boots Sale Nears as Weston Family Eyes $9bn Deal
 BBC Three and Scotland Face Online-Only Future
 Feeld Founders Receive Record Dividend as Sales Rise
 UK Diesel Reaches £2 as Inflation Surges Across Europe
 Minister Rejects Fears of UK Diesel Shortage
 UK Faces Calls to Review Bank Failure Bets
 Informa Agrees £2.24bn Deal to Buy Clarion
 EU-China Talks Target Surge in Hybrid Car Imports
 Samsung Heads for Record Profit as AI Chip Demand Surges
 IMF Warns Governments Over Rising Debt Burdens
 Tesco Raises Profit Forecast as Consumer Confidence Holds
 Ministers Push ATO to Reconsider Credit Card Ban
 Australia Delays Tax Credit Card Payment Ban After Backlash
 Hall and Woodford Win Nobel Economics Prize
 Healey Plans £1bn Online Marketplace Tax Crackdown
 Reform UK funding: mystery billionaire revealed
 UK rejects EV charging VAT cut amid Treasury clash
 Weight-Loss Drugs Transform Fashion Shopping Habits
 EasyJet Takeover Sparks Fears Over Passengers’ Future
 Weight-Loss Drugs Offer Food Savings Mainly to High Earners
 Firms on both sides fear damage from US-Canada trade war
 London Launches First Self-Driving Taxis
 UK House Prices Fall as Mortgage Rates Rise
 McLaren to Create 1,000 UK Jobs in £450m Investment
 Nats Boss Summoned as UK Flight Chaos Continues
 Apple Folding iPhone Set for Major CEO Test
 John Lewis Losses Widen to £124m as Confidence Falls
 Oil Prices Surge as Saudi Pipeline Closure Deepens Crisis
 UK Retailers Accused of Breaking Refund Laws
 Anthropic Backs $31.9bn Queensland Data Centre
 OpenAI Reveals Six Cases of Concerning AI Behaviour
 Japan Raises Rates to 31-Year High
 Tom Watson Takes Senior Role at Palantir
 UK Retail Sales Rebound as Consumers Spend More
 AI Takes Centre Stage in Trump-Xi Talks
 MPs Defend UK Economic Watchdog Against Critics
 AO Acquires Jessops in Camera Retail Expansion
 Xi urges Trump to avoid US-China military conflict
 Saudi intercepts Houthi missiles as oil fears grow
 Should Savers Lock Into 5.25% Fixed Rates?
 Beaverbrooks Boss Calls for Relief on Business Costs
 Trump backs voluntary AI safety pact with tech giants
 Sheikh Tahnoon and the UAE’s AI Ambitions
 UK house price growth slows as mortgage rates rise
 UK borrowing costs surge as global bond sell-off deepens
 UK Bookmakers Linked to Offshore Casino Deal
 French Debt Fears Put Euro Markets Under Pressure
 UK Assures Public Over Diesel Supply
 BT Broadband Pauses Raise Digital Switchover Concerns
 UK Weighs Chinese Car Tariffs Amid EU Trade Push
 BT Agrees £400m TalkTalk Rescue Deal
 Shell Refineries Set for Record Refining Profits
 Japan Beer Giants Face Cartel Probe
 Oil Shock Sends Markets Lower as Middle East Risks Grow
 UK Water Firms Earn Millions From Industrial Wastewater
 UK Savers Face Uncertainty as Rates Rise Above 5%
 UK Must Build Its Own AI to Protect National Security
 IFS Warns UK Budget Faces £35bn Spending Gap
 Parking Apps Push UK Drivers’ Costs Up by 40%
 IMF Warns Global Economy Is Nearing Its Limits
 UK Water Firms Face £107m Bill Reduction Penalties