
Published: 01 October 2026. The English Chronicle Desk. The English Chronicle Online
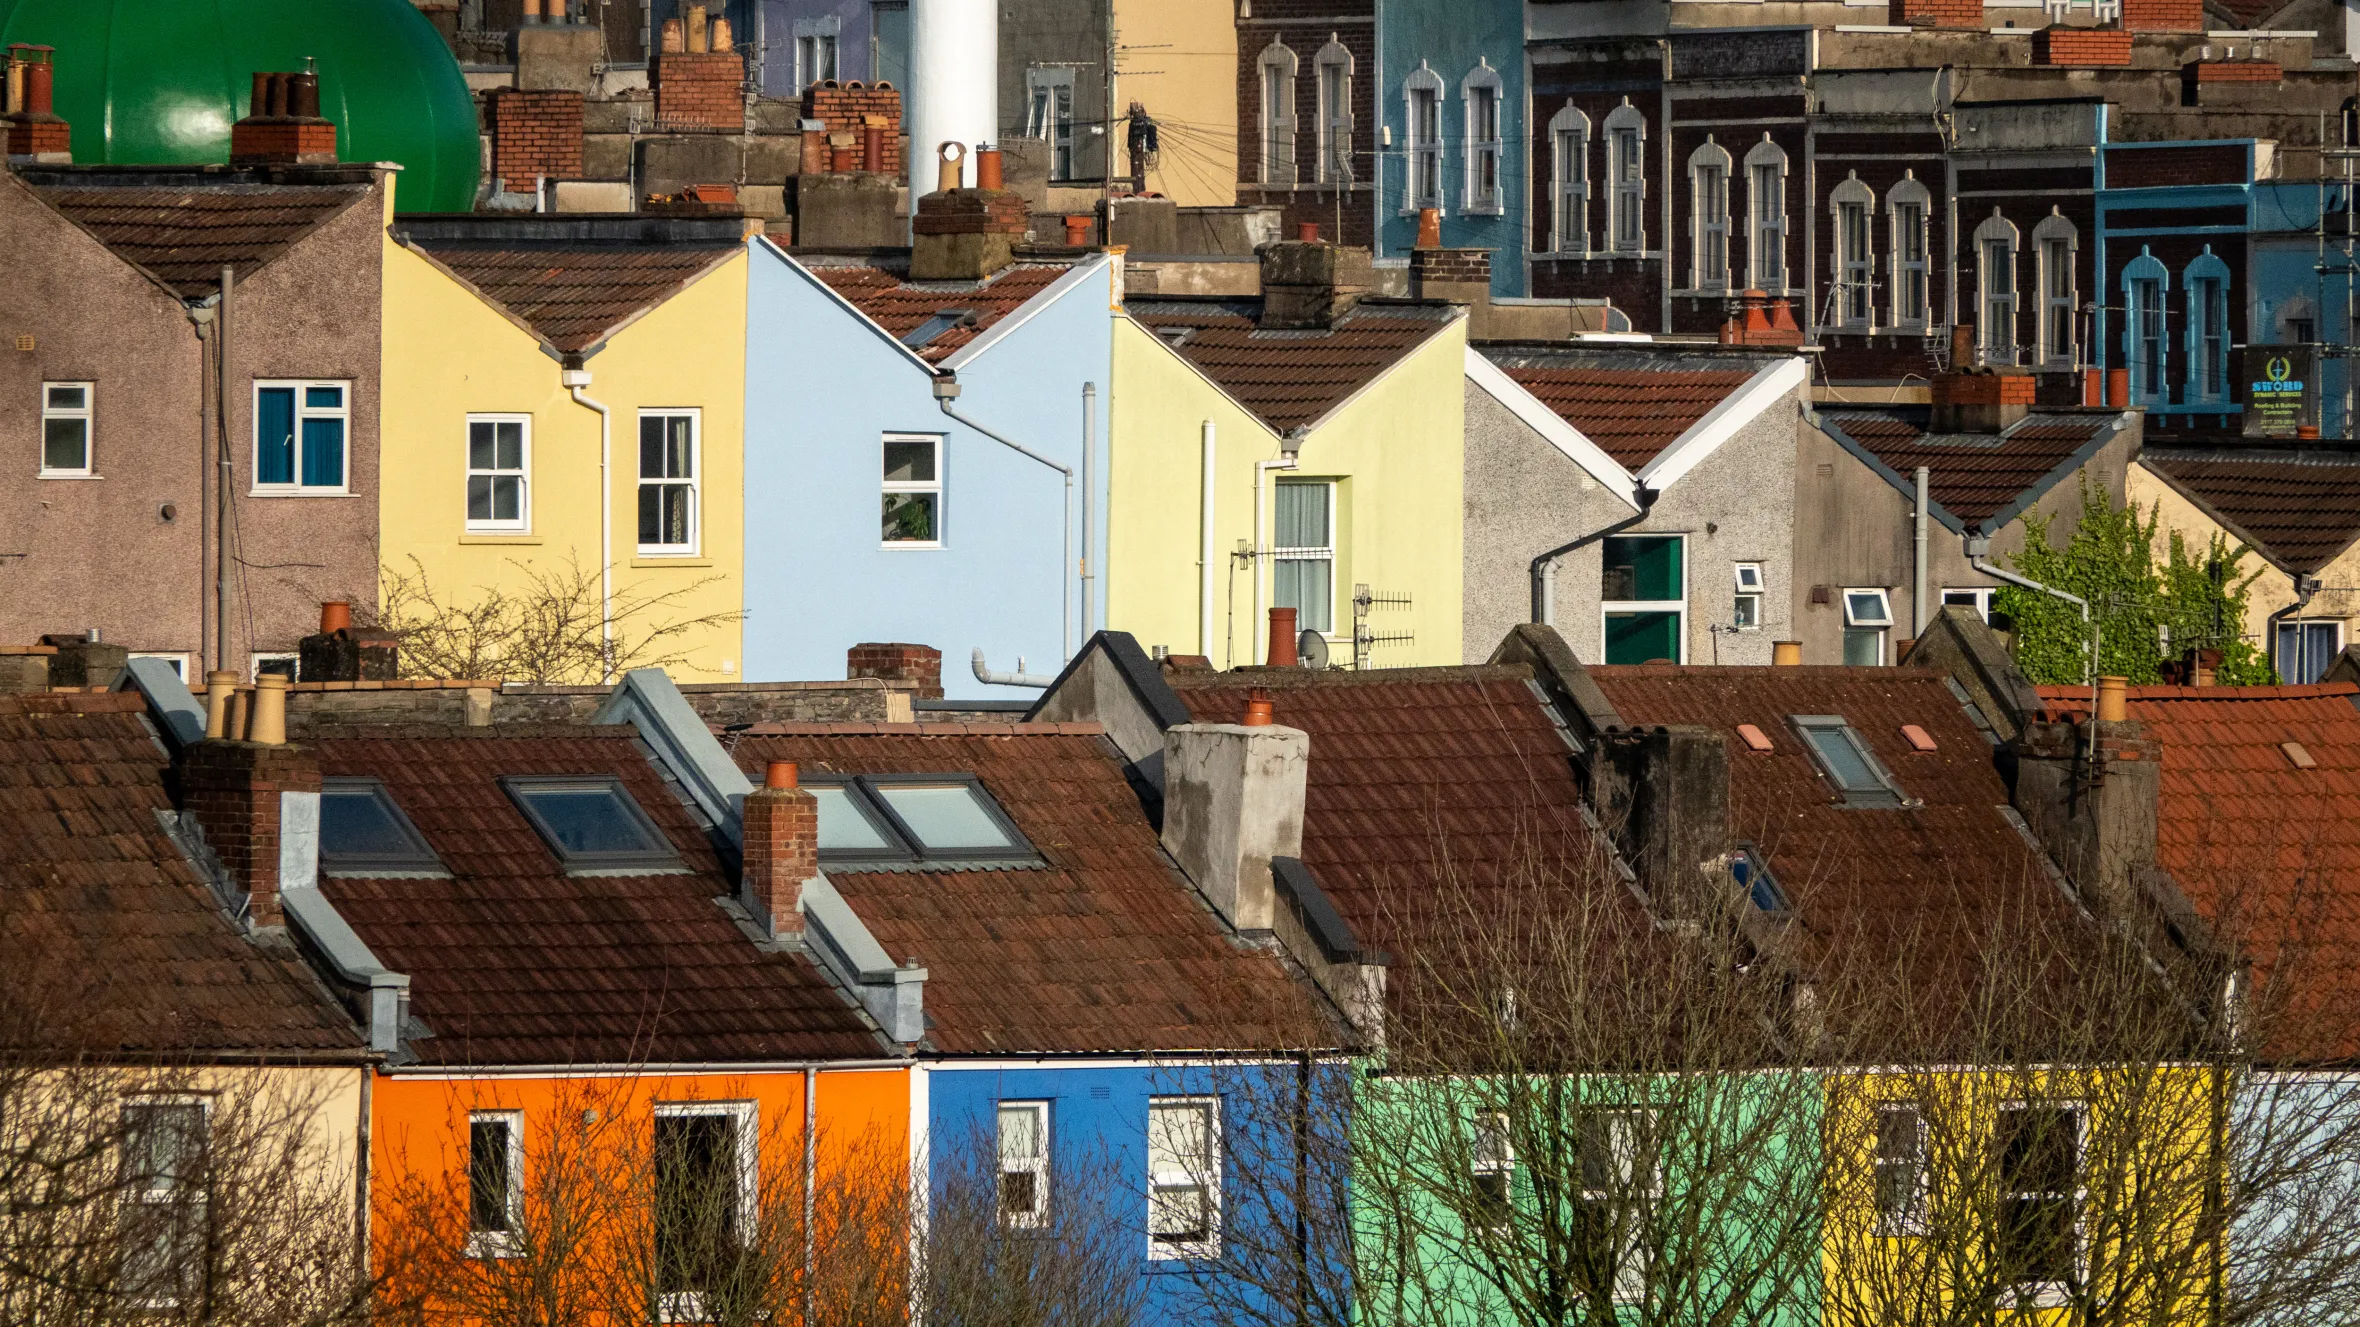
Annual house price growth in the UK slowed sharply in September as higher mortgage costs and continuing economic uncertainty weighed on the housing market, with average property values rising at only half the pace recorded a month earlier.
The average price of a home reached £274,251 in September, according to Nationwide, representing an annual increase of 0.8%. The figure was down from the 1.6% annual growth recorded in August and marked the weakest rate of annual house price growth since December last year.
On a monthly basis, UK house prices declined by 0.2% in September after seasonal adjustments. The latest figures underline the subdued conditions facing buyers and sellers as borrowing costs remain elevated and households continue to assess the wider economic outlook.
The slowdown comes at a particularly uncertain time for the British economy. Developments in the Middle East have contributed to increased volatility in global energy markets, while higher oil and gas prices have added to concerns that inflation could remain above the levels expected by policymakers.
Those pressures have also affected financial markets and mortgage pricing. The cost of borrowing for prospective homeowners has increased as expectations surrounding future interest rates have shifted. For many buyers, higher mortgage payments have reduced the amount they can comfortably borrow, while others may be delaying purchases until there is greater clarity over the direction of interest rates.
Robert Gardner, Nationwide’s chief economist, said geopolitical tensions and the conflict in the Middle East had contributed to upward pressure on energy prices and renewed concerns about inflation. Those developments, he said, had influenced expectations surrounding future Bank of England interest-rate decisions and kept market rates underpinning mortgage prices higher.
Mortgage rates have already moved significantly higher in recent months. Average rates for fixed-rate deals have climbed to levels not seen for several years, increasing the financial burden on households seeking to purchase properties or refinance existing mortgages.
The situation is particularly important for borrowers approaching the end of existing fixed-rate deals. Households that secured mortgages when borrowing costs were lower may face considerably higher monthly payments when they refinance, depending on the size of their outstanding loan and the rate available to them.
Interest-rate expectations have also become more uncertain. Financial markets have been pricing in the possibility of further increases by the Bank of England as policymakers attempt to control inflation. The central bank has a 2% inflation target, but consumer price inflation has remained above that level.
Recent inflation data showed consumer price inflation at 3.1%, increasing pressure on policymakers to ensure that inflation does not become entrenched. The Bank of England has also warned that inflation could move higher in the months ahead if energy costs remain elevated.
For the housing market, the combination of higher mortgage rates and uncertainty over household finances can have a direct impact on demand. Buyers may become more cautious about committing to purchases, while sellers may have to adjust their expectations if there are fewer prospective purchasers able or willing to pay higher prices.
The national figures also mask significant differences between regions. East Anglia recorded the weakest annual performance in September, with house prices declining by 0.7% compared with the same period a year earlier.
Northern Ireland recorded the strongest annual growth, with prices increasing by 5.9%. The contrasting regional performances demonstrate that the UK housing market is not moving uniformly and that local economic conditions, employment patterns, housing supply and affordability can all influence property prices.
Despite the slowdown, the latest figures also contain some signs of improved affordability for people looking to buy. House prices have been increasing more slowly than earnings for an extended period, meaning that the relationship between wages and property values has gradually improved for some households.
Nationwide said this improvement in underlying affordability could eventually support housing-market activity. However, the benefit has been partly offset by higher mortgage rates, which increase the cost of financing a property even when the purchase price itself is not rising rapidly.
The future direction of the housing market is therefore likely to depend heavily on borrowing costs and consumer confidence. If mortgage rates begin to decline and households become more confident about the economic outlook, some buyers who have delayed purchases could return to the market.
At present, however, uncertainty remains significant. The prospect of higher inflation and potentially higher interest rates could continue to place pressure on mortgage costs, while households are also dealing with higher expenses for energy, food and other essentials.
The situation is particularly relevant for first-time buyers, who often face the combined challenge of saving for a deposit and demonstrating that they can afford monthly mortgage payments. Rising property prices over previous years have already made entering the housing market difficult for many younger households.
Government policy is also expected to play a role in the housing market. A new scheme aimed at helping first-time buyers is due to provide additional assistance in England, particularly for people who do not have access to financial support from family members.
Under the scheme, the government will provide an equity loan equivalent to 20% of the purchase price, while eligible buyers will be able to contribute a minimum deposit of 2.5%. The buyer would therefore need a conventional mortgage covering 77.5% of the property value.
The initiative applies to new-build homes in England and is designed to reduce the size of the deposit required from eligible first-time buyers. By lowering the initial financial barrier, policymakers hope to make home ownership more accessible to people who have struggled to accumulate a large deposit.
The prospect of increased activity among first-time buyers has also attracted attention from housebuilders, with several major companies seeing movements in their share prices following developments surrounding the scheme.
However, government assistance cannot entirely remove the impact of mortgage rates. Even with a smaller deposit requirement, buyers still need to demonstrate that they can afford the associated mortgage repayments. Higher interest rates can therefore continue to limit purchasing power.
For existing homeowners, the current environment presents a different set of challenges. Those who are not planning to move may nevertheless face higher borrowing costs when refinancing. Some households could respond by extending mortgage terms, reducing other spending or delaying major financial decisions.
The wider housing market may consequently remain subdued until there is greater certainty over inflation and interest rates. Estate agents, mortgage providers, housebuilders and potential buyers are all likely to be watching developments at the Bank of England closely.
The September figures do not indicate a uniform decline across the entire UK housing market, but they do show that annual growth has lost momentum. With the average property price now standing at £274,251, the market is entering the final months of the year under pressure from borrowing costs and wider economic uncertainty.

The key question for the months ahead will be whether improving affordability relative to earnings can offset the impact of higher mortgage rates. A sustained improvement in household confidence, combined with lower market borrowing costs, could encourage more buyers to return. Conversely, continued inflationary pressure could keep financing costs elevated and prolong the period of weak housing-market activity.
For households considering buying or selling, the September figures underline the importance of looking beyond headline national price movements. Regional conditions, mortgage rates, household income and individual financial circumstances remain central to the actual cost and affordability of a home.
As Britain enters the final quarter of 2026, the housing market therefore remains closely tied to the broader economic picture. The slowdown in annual house price growth reflects a cautious market in which buyers are balancing the long-term goal of home ownership against the immediate reality of higher borrowing costs and uncertain economic conditions.
Related News:
 UK House Prices Fall as Mortgage Rates Rise
 Oil nears $100 as Saudi attacks shake markets
 Thames Water Revises Oxfordshire Mega-Reservoir Plan
 UK Retail Sales Rebound as Consumers Spend More
 UK Borrowing Hits £18.3bn Ahead of Budget
 Thinktank Calls for Abolition of UK State Pension
 MPs Defend UK Economic Watchdog Against Critics
 UK Trade Losses Grow Without EU Product Deal
 Should Savers Lock Into 5.25% Fixed Rates?
 UK Diesel Prices Hit Record High Amid Iran Conflict
 Poundland Rescue Bid Could Protect 11,000 Jobs
 Wealthy Britons Flee Gulf War but Avoid UK Taxes
 UK Wage Growth Slows as Jobs Market Holds Firm
 BBC News Faces Deep Cuts in 2,000 Job Plan
 New UK advice scheme to boost savings and investing
 Reeves Fights to Keep Treasury Role Amid Labour Turmoil
 UK rejects EV charging VAT cut amid Treasury clash
 EasyJet Takeover Sparks Fears Over Passengers’ Future
 Europe Faces Winter Gas Supply Anxiety
 UK Households Could Save £173 on Fixed Energy Deals
 Burnham Faces Mounting Budget Challenges
 Dutch Bank Moves 86 Tonnes of Gold to London
 UK Cost Squeeze Deepens as Mortgages and Gas Rise
 Billionaire Chris Rokos poised to leave UK
 JPMorgan Boss Warns Against UK Bank Tax Rise
 John Lewis Losses Widen to £124m as Confidence Falls
 UK State Pension Set to Rise 3.9% as Triple Lock Holds
 UK Parents Cut School Uniform Costs as Prices Rise
 UK Pay Growth Slows to 3.9% as Rate Decision Nears
 Bank Urged to Slow Bond Sales as UK Costs Rise
 UK Inflation Hits 3.1% as Household Pressure Grows
 UK Productivity Improves as Bank Weighs Interest Rates
 Japan Raises Rates to 31-Year High
 UK Rent Gap Puts Low-Income Families Under Pressure
 Calls Grow to Expand UK National Wealth Fund
 Chinese Hybrid Car Surge Raises EU Auto Industry Concerns
 Tony Blair Calls for Britain to Rejoin EU Within a Decade
 AO Acquires Jessops in Camera Retail Expansion
 Saudi intercepts Houthi missiles as oil fears grow
 Beaverbrooks Boss Calls for Relief on Business Costs
 Why Americans Feel Ripped Off by Rising Prices
 New UK Homes in Flood Zones Face Insurance Risk
 Ukraine Faces $45m Hourly Cost From Missile Alerts
 Healey urged to act as UK energy bills rise 4%
 UK Doubles Steel Tariffs to 50% to Protect Domestic Plants
 Oil and Gas Prices Surge Amid Iran-Israel Attacks on Gasfields
 Student Loan Interest May Rise Despite 6% Cap
 Carmakers Face £3bn Gap in UK Loan Payout Scandal
 Albanese Rejects Gas Export Tax Push
 Spirit Airlines shuts down after 34 years amid crisis
 UK Pushes for New EU Goods Trade Deal
 UK firms accused of ‘AI washing’ boom
 Severn Trent CEO Reward Package Doubled Despite Public Anger
 Weight-Loss Drugs Transform Fashion Shopping Habits
 Labour MPs Urge Burnham to Revive UK Aid Target
 Canada to Match Trump’s 50% Tariffs Dollar for Dollar
 Pubs and Hotels Face Business Rates Reform Review
 Firms on both sides fear damage from US-Canada trade war
 US CEOs Earn 614 Times More Than Workers
 Trump Hardens Canada Trade Stance as Talks Stall
 UK Subsidence Claims Surge After Record-Breaking Summer
 Reform Faces Fresh Financial Controversy
 Spire Healthcare Agrees £1bn Takeover by Toscafund
 Oil Prices Surge as Saudi Pipeline Closure Deepens Crisis
 UK Retailers Accused of Breaking Refund Laws
 North Sea Firms Urge Early End to Windfall Tax
 UK Youth Jobs Gap Reveals Deep Regional Divide
 Entain Plans 400 Job Cuts After Profit Update
 Next Raises Profit Forecast After Strong Summer Sales
 Tories Press Healey Over Tax Rises Ahead of Budget
 Trump Threatens EU With Tariffs Over Canada Proposal
 Trump Threatens EU Over Canada Partnership Proposal
 Barclays Staff Push Back Against Office Return Plan
 Reform UK Faces Internal Debate Over £72m Spending
 Labour Apprenticeship Scheme Faces Slow Start
 Trump Eyes Major Belarus Fertiliser Deal Amid Canada Trade Dispute
 Iran Rejects Claims of Shift in US Talks
 TalkTalk Races to Sell Arms as Administration Looms
 Burnham Opens Door to Possible UK Return to EU
 Bank Chief Calls for Power to Intervene in AI